Personal Financial Management
Insights, budgeting, goals, categorisation and financial wellbeing
Help customers understand their money
Personal financial management, or PFM, uses financial information to help customers inspect spending, plan budgets and track goals. A summary or forecast is an interpretation of available data, not necessarily a complete account of the customer's finances or a regulated recommendation.
State which accounts and periods are included and when information was updated. Separate observed facts from estimates. A connected account may omit cash activity, other accounts or obligations, and a delayed feed can make a current-looking chart incomplete.
Capture and categorise carefully
Distinguish pending activity, posted transactions, reversals and transfers between the customer's own accounts. Avoid counting a card authorisation and its later posting as two purchases. Link duplicates using suitable source identifiers rather than matching only amount and date.
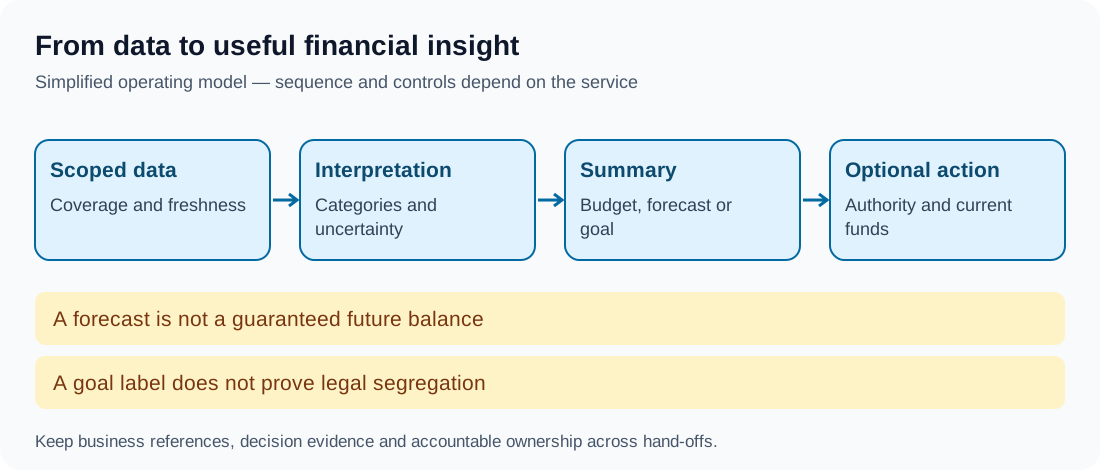
Merchant or text categorisation is an inference. A supermarket payment can contain goods outside one category; a transfer to a named person may be rent. Offer correction where appropriate and explain how customer overrides interact with future updates. Category uncertainty should not silently become a definitive credit or vulnerability assessment.
Budgets, forecasts and goals
Explain assumptions about recurring income, bills, timing and included balances. A forecast can show an expected shortfall with uncertainty; it should not promise the customer will have a particular future available balance. Separate a goal label from a legally segregated or protected account.
If a saving rule moves money, establish its authority, timing, limits and failure behaviour. An insight dashboard alone does not authorise transfers. Check current available funds and product conditions at the effect boundary, and provide a clear way to modify or stop applicable future actions.
Household and connected-account boundaries
Access to one family member's account does not grant visibility of another's. Shared budgets need explicit roles and appropriate information boundaries. Financial abuse and confidentiality risks deserve consideration, including whether notifications could expose sensitive choices.
For external accounts, use the applicable data-access permission and provider arrangement. Revocation or feed interruption should change the displayed coverage and freshness. A disconnected account is not a zero balance. Preserve necessary records under the relevant retention policy without treating old access as unlimited future permission.
Worked example: a refund and an own-account transfer
In this fictional budget, a salary arrives, a customer transfers money between their two included accounts and a merchant refunds a purchase. A naive total labels all three as new income and overstates spendable resources.
The service distinguishes the internal transfer and links the refund to its relevant spending context. It presents the revised summary with its assumptions. Before an optional sweep executes, the payment service checks actual current funds; the budget chart does not control the ledger balance.
Support and commercial uses
Wellbeing tools can help people inspect choices without diagnosing their condition or pressuring them to borrow. Review a commercial offer attached to an inferred shortfall as an offer, with the relevant product and promotion obligations. Calling it an insight does not remove those duties.
Measure accuracy, corrections, comprehension, task completion and complaints. Test late data, changed categories, missing accounts, currency conversions and duplicate events. Financial guidance, personal recommendations and automated significant decisions can attract different rules; assess the actual activity in its market.
Public reference and application
The World Bank Global Findex 2025 examines financial inclusion, connectivity and digital safety. Access to an app alone should not be treated as proof of improved financial wellbeing.
Takeaway
PFM helps when its coverage, categories and assumptions are understandable. Any action that changes money or sells a product needs the controls of that action, beyond the usefulness of the chart.
Continue to Digital Accessibility.