Digital Accounts
Instant access, virtual features, controls and digital servicing
The account beneath the interface
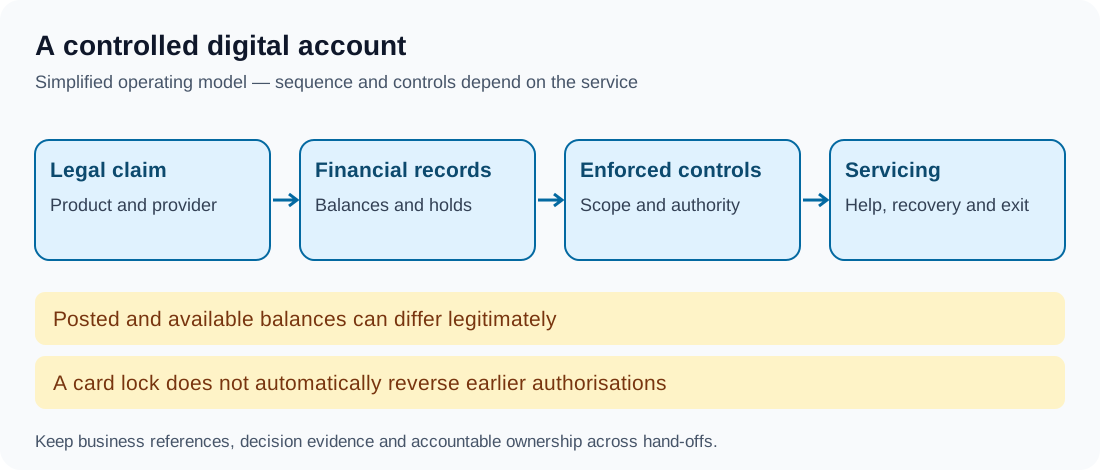
A digital account is opened or serviced through electronic channels. The channel does not determine the legal claim. A bank deposit, e-money balance, safeguarded payment funds and a platform credit can all appear as a balance but have different rights and protection.
Name the provider, product and relevant terms. Explain funding, available actions, charges, interest where applicable and access or closure conditions. An account number or wallet label does not establish that the customer holds a directly insured bank deposit.
Balance semantics and financial records
Distinguish posted balance, pending items, holds and available funds. Availability can include authorised overdraft or credit and can differ from posted balance without an error. The important control is an accurate definition and reconciliation, not forcing every screen and statement to show one identical number.
Early access to expected incoming money may involve credit or provisional availability under the arrangement. Explain conditions and what happens if the incoming transaction fails or returns. Do not describe a forecast receipt as final settlement. Reconcile adjustments and related customer obligations separately.
For a scoped US example, the FDIC's third-party-app guidance explains that nonbanks are not themselves insured and pass-through deposit coverage has conditions. Other markets and products have different protection and safeguarding frameworks.
Controls need real effect and clear scope
Card locks, account restrictions, limits and user permissions are different controls. Establish where each is enforced and which transaction types it affects. A UI change alone cannot prevent a direct API call, a previously authorised clearing item or an offline transaction where the actual arrangement permits it.
For card credentials and tokens, coordinate the relevant issuer and token lifecycle processes. Explain what a temporary lock or replacement does rather than promising all activity becomes impossible instantly. Verify the effect and investigate pending or exceptional transactions under the appropriate process.
Servicing, recovery and exit
Link statements, transactions, fees, cases and customer actions using durable identifiers. Account recovery and contact changes need appropriate authentication and authority, including the risk of compromised new details. Notifications should reflect current status without exposing unnecessary information.
Closure can require handling pending transactions, outstanding credit, recurring arrangements and retained records. Define actual product and legal conditions and communicate the result. Stopping an app login does not automatically close the financial account or cancel every related agreement.
Worked example: pending card payment
In this fictional account, a card authorisation reduces available funds while the posted balance is unchanged. Later clearing posts the purchase and releases the corresponding hold. The app explains both states and avoids subtracting the purchase twice.
The customer locks the card before clearing. The bank follows the actual control scope and explains why an already authorised item may still post. Support uses the original reference and status history; it does not promise that locking the card reverses the purchase.
Operating assurance
Test partial account creation, duplicate instructions, holds, returns, restrictions, token changes, recovery and closure. Monitor unexplained balance differences, unresolved effects, aged cases and incorrect protection claims. App uptime does not establish that all customer entitlements reconcile.
Takeaway
A digital account needs a clear legal claim and accurate balance semantics. Its controls and servicing should work in the financial systems, with customer messages that describe their actual effects.
Continue to Digital Lending.