Digital Lending
Data driven origination, instant decisions and automated servicing
A digital process for a continuing obligation
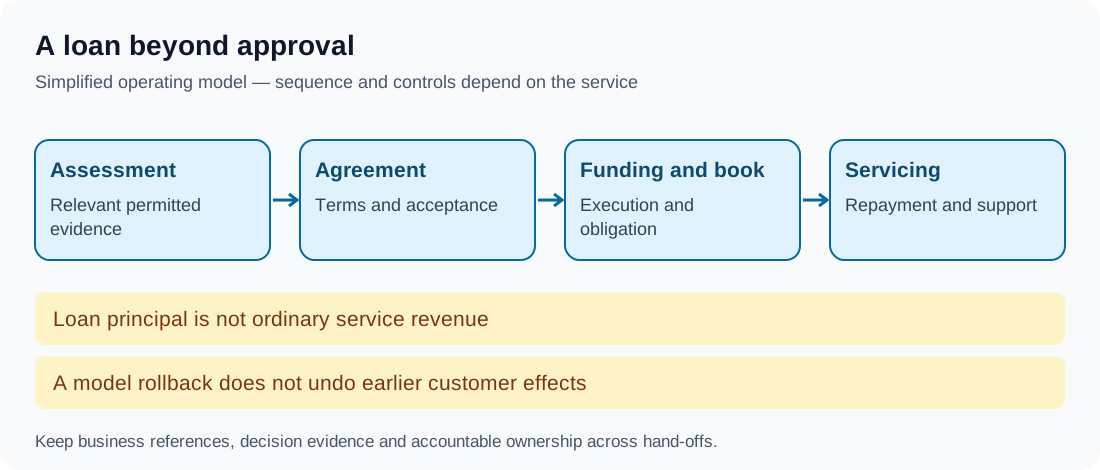
Digital lending originates and services credit through electronic channels. It can reduce delay and manual work, but the firm still needs an appropriate assessment, agreement, creditor record and servicing process. Fast approval is not evidence of sustainable credit or a loan already funded.
Identify the borrower, creditor, product, distribution channel and relevant rights. Consumer, SME, secured and unsecured products have different assessment and legal conditions. Customer information should distinguish a quote, provisional offer, approval, executed agreement and disbursement.
Assessment and decision evidence
Use relevant, permitted data with understood coverage and quality. Assess repayment capacity, creditworthiness, fraud and product conditions under the actual framework. A merchant sales feed or behavioural score does not automatically describe complete income and obligations.
Record the important sources, transformations, decision versions and reasons with appropriate retention. Preserve what was known at decision time rather than silently replacing it with later data. Review and challenge routes should have relevant evidence and authority; a mandatory human review is not a universal requirement for every digital decision.
The EBA loan-origination and monitoring guidelines illustrate a scoped EU framework for assessment and lifecycle governance. Required notices and reasons also differ; US Regulation B's interpretation addresses specific adverse-action reasons grounded in factors actually used.
Agreement, funding and accounting
Explain relevant price, instalments, charges, conditions and consequences before the customer commits. Keep agreement versions and acceptance evidence. Authority to collect repayment is a separate part of the actual arrangement, not an assumed consequence of possessing account details.
Join the credit contract to disbursement, principal balance, interest, fees and schedule. Loan principal is not service revenue. Accounting follows the applicable financial-instrument framework and facts; do not assume every fee is earned immediately or recognised identically across products.
Servicing is more than a reminder
Provide statements, corrections, repayment changes, early settlement, disputes and hardship routes as applicable. Automated notices should use the current obligation and customer status. A chatbot cannot agree a new legal repayment arrangement beyond its approved authority.
Collections need controls for timing, duplicates, failed payment and changes in mandate or debt. A return, refund or cancellation can affect credit through the applicable linked process; a commerce event does not always automatically extinguish every debt. Explain unresolved states and prevent avoidable incorrect collection.
Worked example: stale income
In this fictional assessment, a salary feature comes from an outdated feed and omits a known change. The application is referred under the product policy for appropriate additional evidence. The reviewer distinguishes missing or stale information from proof that the applicant misrepresented income.
If a defect affected completed decisions, the lender identifies the relevant population and assesses remediation. Replacing the model only changes future processing; it does not resolve earlier agreements or customer harm by itself.
Risk and performance
Monitor cohorts over a relevant maturity horizon, losses, arrears, complaints, hardship outcomes and decision errors. Separate origination volume from funded balances and risk-adjusted economics. Test concurrent approvals, duplicate loans, failed disbursements, repayment races and provider continuity.
Takeaway
Digital lending connects an evidenced assessment to a real credit obligation and continuing service. Decision speed is useful when the contract, money movement, book and customer support remain consistent.
Continue to Buy Now Pay Later.