Lynx RTGS, Settlement and Finality. Explain real-time gross settlement, settlement evidence, irrevocability and finality.
Canada Payments & Collections · Block 8 · Chapter 38 of 75
This chapter explains the heart of Lynx: real-time gross settlement in central-bank money, the evidence that proves a settlement happened, and what finality actually promises — and what it does not. Chapter 36 introduced Lynx as Canada's high-value system and Chapter 37 walked the customer credit transfer message; this chapter answers the question every banker, treasurer, and operations analyst must be able to answer on demand: when is a Lynx payment truly finished, who can rely on it, and what proof stands behind the answer.
The scope set for this chapter is precise: the RTGS model payment by payment, the settlement evidence chain, irrevocability and finality in functional terms, queue and priority paths, end-of-cycle procedures at functional level, and the three finalities every desk must keep separate. Message construction belongs to the pacs chapters; participation models and exception mechanics live in their own chapters.
A note on status dates. Baseline is October 5, 2026. Lynx, owned and operated by Payments Canada with the Bank of Canada as settlement agent and overseer, has been live since 1 September 2021, when it replaced the Large Value Transfer System, and is designated a systemically important payment system. Its ISO 20022 migration completed with the full move from MT to MX messages in November 2025. This chapter describes rules functionally — what they achieve, who they bind, and where the boundary sits — without quoting legal text. Where exact rule language matters, go to the authoritative sources in Section 12.
What you should be able to do after this chapter
After working through this chapter, you should be able to:
- explain real-time gross settlement in plain language: what settles, when, in whose money, across whose accounts, and why payment-by-payment matters;
- contrast RTGS with deferred-net settlement on liquidity, timing, finality, and return rights, and choose the right model from business facts;
- describe the settlement evidence chain — Lynx message confirmation, Bank of Canada account entries, participant books, statements and advices — and say which link proves what;
- define irrevocability and finality functionally, locate the exact boundary where they attach, and explain why nothing before that line is final;
- distinguish settlement finality from beneficiary availability and from underlying commercial finality, and correct anyone who merges them;
- trace urgent versus queued settlement paths, explain why a released payment can wait, and state what treasury and operations each own while it waits;
- explain end-of-cycle procedures functionally: what closes, what carries, what gets proven before the next cycle;
- place fraud, sanctions, AML, and operational controls at the correct gates relative to the finality boundary;
- classify post-settlement problems correctly — recall request, linked reversal where permitted, investigation — and explain why unilateral return is gone;
- explain posting, accounting, liquidity, reporting, and reconciliation for RTGS from a bank operations view;
- describe what a bank must build, test, and staff before trusting its Lynx settlement operation;
- work through fictional Canadian examples — a supplier release, a queued month-end payment, and an erroneous duplicate — and extract the control lesson from each;
- navigate confidently to the authoritative references and know which document answers which question.
For a roughly 60-minute core session, spend 10 minutes on Sections 1–2, 20 minutes on Sections 3–4 with the boundary and evidence diagrams, 10 minutes on Sections 5–6, 10 minutes on Sections 7–9 with the queued-paths diagram, and 10 minutes on Section 11 examples plus Section 12 takeaways.
Chapter navigator
- Business context and customer need
- Participants, responsibilities and system boundaries
- Initiation, validation and bank processing
- Clearing, settlement and finality — the RTGS core
- Data, identifiers, messages and references
- Rules, service levels, operating day and customer impact
- Fraud, compliance and operational controls
- Exceptions, investigations and recovery
- Posting, accounting, liquidity, reporting and reconciliation
- Bank implementation, testing and resilience
- Practical Canadian end-to-end examples
- Key takeaways and authoritative references
1. Business context and customer need
Nobody wakes up wanting real-time gross settlement. A Toronto manufacturer wants steel released from a Calgary supplier today, and the supplier will only release against money that cannot be taken back. A law firm holding house-closing funds wants the seller's lawyer to see value that is beyond recall before keys change hands. A corporate treasurer covering a foreign-exchange settlement wants the Canadian-dollar leg discharged with certainty before the dealing room closes its books. A bank treasurer moving funds between institutions wants the interbank leg finished, provably, in the same moment it is agreed. Each of these customers uses different words — release, closing, cover, settle up — but they are all asking for the same product attribute: finality, now, with proof.
That is the business need Lynx exists to serve, and this chapter keeps returning to it because settlement mechanics are easy to admire and easy to mis-sell. RTGS is not valuable because it is fast in the colloquial sense; batch systems move enormous volumes efficiently and most Canadian payments never need gross settlement. RTGS is valuable because it collapses the dangerous gap between agreement and discharge. In a deferred-net world, a payment can be agreed, exchanged, even shown to a customer, while interbank value still sits in a future funding event exposed to return rights and participant failure. In Lynx, each payment is discharged individually, in central-bank money, in the moment — and the rules then treat it as finished. The customer is not buying speed. The customer is buying the right to stop worrying.
Consider what that purchase is worth. A supplier owed CAD 4.2 million will not ship against a promise that might return or unwind; it ships against a Lynx confirmation because the participants have already exchanged central-bank value with no path back except cooperation. A house closing cannot proceed on a batch credit whose return window still runs. A pension fund meeting a margin call needs a timestamp its counterparties accept without argument. Beside those risks, the wire fee and liquidity cost are trivial. When you advise between batch and Lynx, translate the fee into the deal's language: what does one more day of doubt cost, and who bears it.
The bank sits between that commercial urgency and the settlement engine, and its job is harder than it looks. It must take an instruction that arrives through ordinary channels — a corporate host-to-host file, a dealing-room terminal, a branch visit with nervous first-time buyers — and convert it into an obligation the bank is willing to make irrevocable. That conversion is the whole of Sections 2 through 7: validate twice because there is no unilateral way back, check liquidity because gross settlement demands full funding per payment, screen and approve because fraud caught after settlement is a negotiation rather than a reversal, and release only when every gate has recorded its decision. A bank that treats a wire like a faster batch payment — same validation depth, same casual approvals, same vague customer language — will eventually release a payment it cannot recover and discover the meaning of irrevocable through loss rather than through study.
Scale sharpens the point. Payments Canada reports 2025 Lynx totals of 13.6 million items and CAD 93.3 trillion in value, or daily averages of 54,229 items and CAD 371.9 billion. These are system statistics, not a customer-volume forecast. Each settled obligation still deserves validation, liquidity, and evidence at payment grain. Lynx is not a deferred retail batch: its LSM can recycle liquidity and use the Gridlock Buster to offset queued payments, but settlement remains governed by Lynx's individual payment obligations and settlement mechanisms. Spend the validation budget before release, staff approval discipline there, fund liquidity deliberately, and make settlement a quiet, provable event.
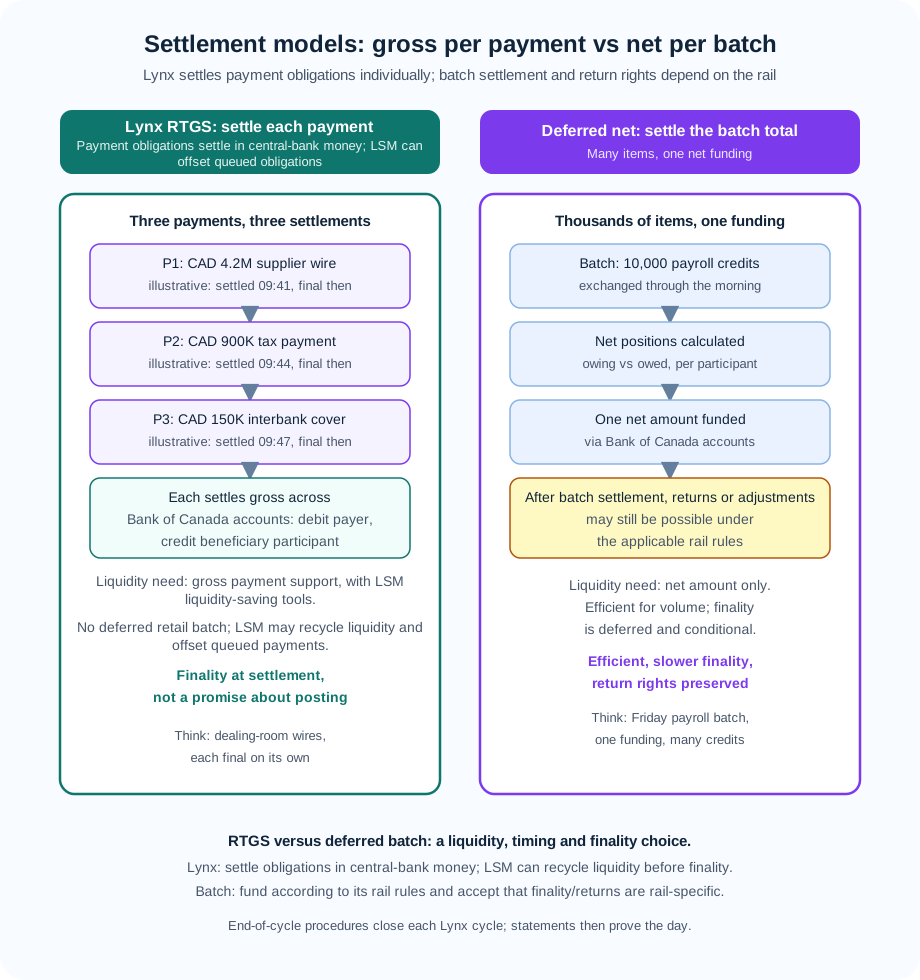
The diagram above is the chapter's anchor. Keep it open as you read: every section either moves a payment toward the left column's per-payment certainty or explains what the bank must do to deserve it. When later chapters discuss messages, queues, liquidity tools, or investigations, locate yourself on this picture first — which column am I in, and which side of the finality line?
A final framing point before the detail. Settlement finality is a system promise about the interbank leg. It says the participants have exchanged value that the system will not unwind. It does not by itself say the beneficiary can spend the money yet: By-law No. 9 section 36 separately governs when the receiving participant must make the payment finally and irrevocably available to the payee. And it does not say the underlying commercial deal is closed — invoices can still be disputed, goods can still be rejected, contracts can still be litigated. Three finalities, three owners, three clocks. Section 4 defines them, Section 6 prices and promises them, and the customer-promise diagram makes them unforgettable.
2. Participants, responsibilities and system boundaries
Settlement looks instantaneous from the outside, which tempts newcomers to imagine two parties — sender and receiver — and one machine in the middle. The real cast is larger, and each member owns a bounded piece of the certainty the customer buys. Blurring these responsibilities is how settlement incidents start: everyone assumes someone else checked liquidity, validated the message, or told the customer the truth about timing.
The originator — the corporate treasury team, the law firm, the individual buyer, the bank's own treasury desk for interbank payments — creates the instruction and owns everything the system cannot verify: the commercial purpose, the correct beneficiary, the right amount and date, and the authority to instruct. For Lynx this responsibility weighs more than on any batch rail, because the originator's error becomes irrevocable value within moments. A transposed account number on a batch item comes back as a coded return; the same error on a wire becomes a recall request that depends on a stranger's cooperation. Banks under-invest in originator discipline at their peril: confirmation of beneficiary details, callback discipline for changed instructions, dual preparation and approval in corporate channels, and plain-language warnings that wires cannot be pulled back are not customer-service extras. They are settlement controls that happen to sit outside the bank's walls.
The sending participant — the Lynx direct participant that holds a settlement account at the Bank of Canada — owns validation, liquidity, release, and the customer relationship on the sending side. It validates the instruction in full, confirms funding for the gross amount, applies fraud and sanctions gates, obtains approvals, releases the ISO 20022 message into Lynx, monitors its path to settlement, and reports the outcome with references. Critically, it also owns the decision to stop. A participant that cannot queue honestly, reject cleanly, or hold for screening cannot operate an irrevocable rail safely. Release authority here is the most consequential signature in Canadian retail and commercial payments: it converts a validated instruction into value that cannot be unilaterally recovered.
The receiving participant owns receipt, inbound validation, customer posting, availability, and beneficiary communication. Once Lynx reports settlement it holds central-bank value with no interbank risk — but its work continues: post the correct account, apply availability policy and lawful holds, generate advices quoting settlement references, and answer beneficiary questions without confusing system finality with spendable funds. The sending side says "settled at 10:02" while the beneficiary sees no money yet; both can be true, and Section 6 teaches the language that keeps them from sounding contradictory.
Payments Canada owns and operates Lynx under the Canadian Payments Act framework. It provides the settlement engine and the network, maintains the by-law, rules, and procedures that govern participation and conduct, sets the operating calendar, and manages the system's evolution — including the ISO 20022 migration completed in 2025. It does not judge the underlying commercial deal, does not hold customer accounts, and does not decide whether a particular wire should have been sent. When this chapter says "the system," it means this operated infrastructure plus its rulebook: the thing that accepts messages, checks liquidity and priority, moves central-bank value, and declares finality.
The Bank of Canada plays two roles that newcomers constantly collapse into one, and separating them is worth a minute. First, settlement agent: Lynx payments settle across settlement accounts held at the Bank, so central-bank money is the discharge medium — the reason a settled Lynx payment carries no interbank credit risk on that leg. Second, overseer of designated systems: Lynx is designated systemically important, which brings standards, supervision, and expectations about safety, resilience, and risk management. Settlement agency is daily plumbing; oversight is designation and standards. "Who stands behind this payment" depends on which role is meant: the plumbing answer is central-bank money moved between accounts; the oversight answer is a supervised systemic infrastructure.
Correspondents, intermediaries, and service providers complete the map for payments that touch foreign currency or cross-border legs. A Canadian-dollar Lynx payment settles in Lynx; but a customer instruction that arrives via SWIFT, or a wire that funds a cross-border chain, involves instructing messages and correspondent books alongside the Lynx leg. The sending participant remains responsible to its customer for the whole promise it made: validation, screening, charges transparency, value-date honesty, and tracking across every leg. SWIFT messages instruct and inform; correspondents move value on their own books or foreign rails; Lynx settles the Canadian-dollar interbank leg finally. Never let a customer — or a colleague — believe the SWIFT message was the settlement.
Two boundary principles recur through the rest of the chapter. First, the settlement account boundary is where finality lives. Everything the sending bank does before its settlement account is debited is preparation; everything after is consequence. Design every control, every status message, and every investigation around that line. Second, every boundary needs a handoff record — channel to hub, hub to gateway, gateway to Lynx, Lynx confirmation to posting engine, posting to advice — each timestamped and reference-keyed with the bank-generated references intact and the PCRN added by Lynx after settlement. Settlement is fast; proof must be faster to retrieve than the payment was to send, because the first question after any problem will be "exactly where is it, and exactly when did it cross the line."
3. Initiation, validation and bank processing
Stages 1 through 3 decide whether settlement is a formality or a gamble. Because Lynx offers no unilateral way back, everything this section describes must happen before release, to a standard batch operations would consider excessive. That is not inefficiency. It is the price of irrevocability, paid where it is cheapest — before value moves — rather than where it is dearest, after.
Initiation captures the customer's intent in a form the bank can make irrevocable without guessing. Channels vary: corporate host-to-host and file upload for supplier payments and treasury flows, dealing-room terminals for foreign-exchange covers and interbank moves, online business banking for mid-size wires, branch and contact centre for assisted payments such as house closings and estate disbursements. Good initiation collects the minimum complete dataset and refuses to proceed without it: who pays, who is paid with full beneficiary detail, how much in what currency, on what date, with what references, under whose authority, and for what declared purpose where screening needs it. It binds authentication to the instruction at a strength matched to irrevocable value, and for business payments it enforces release discipline — who prepared, who approved, whether dual approval applied, and whether the instruction was released exactly once.
Initiation on an irrevocable rail must also do something batch initiation can afford to do loosely: make the customer confront finality before instructing. A corporate user who has sent batch files for years will carry batch instincts — "we can reverse it tomorrow," "the bank can pull it back," "let's send now and fix the details after." The initiation experience must break those instincts kindly but firmly: confirmation screens that state the payment becomes final and irrevocable on settlement, explicit beneficiary-detail confirmation for new payees, amount-in-words orFonction-style amount checks for large values, and a final deliberate release action rather than an accidental double-click. Test every channel against one question: can a reasonable user release CAD 4.2 million by accident, and would the bank notice before settlement? If the answer to either half is yes, initiation is not finished.
Validation is the layered set of gates that earns the right to move central-bank money. Format and completeness in the rail's own terms — a well-formed ISO 20022 message with valid routing, reachable beneficiary agent, and all mandatory elements present. Authority — mandate on file, preparation and approval by different hands above threshold, release authority that matches the amount and the customer agreement. Funds and limits — balance plus fees within intraday, customer, and file-level limits, checked against the gross amount because netting will not reduce it. Duplicates — hashes and references against recent history, because a retried file or a double-clicked release on this rail pays twice with no automatic way back. Reachability — destination participant reachable in Lynx on the intended date, beneficiary detail structurally valid. Risk and compliance — fraud scoring resolved to a decision, sanctions screening completed with false positives dispositioned and recorded, AML review where the corridor demands it — all before release, because holding before release is always cheaper than negotiating after settlement.
Validation outcomes must be explicit and legible, because silent validation creates the reconciliation mysteries that surface days later. Accepted means the payment may proceed toward release. Rejected means the bank stopped it before release and must tell the initiator why with repair-grade specificity — which field, which rule, what to fix, by when. Held means it awaits approval, funding, or screening disposition, with a named owner and a visible clock; held payments need active management, not silent ageing, because cutoffs and customer expectations keep moving. Repaired means a defect was corrected under controlled rules and the payment re-validated from scratch, never patched on the way through. Strong Lynx operations reject early and in writing. Every rejection kept in the instruction's history is an investigation that will never need to happen.
Bank processing and routing turns a validated instruction into a releasable Lynx obligation. Enrichment adds what the network needs: routing to the correct beneficiary participant, value-date assignment consistent with the operating day, charge handling, and reference propagation — the bank instruction reference, end-to-end identification and UETR where applicable — carried intact into the pacs.008 or pacs.009. The PCRN is not an input: Lynx generates it only after settlement and returns it with the payment confirmation. The routing decision itself deserves a deliberate record even when Lynx is the obvious choice: why this rail, which rule fired, who approved the choice, and what fallback was considered. When a customer later asks why a time-critical payment went by batch, or why a routine payment consumed intraday liquidity, the bank should show the decision rather than reconstruct it from memory.
Processing also owns scheduling and the release moment. Future-dated instructions are warehoused with triggers tied to the operating day and the bank's internal cutoffs, re-validated at release rather than trusted from days earlier — sanctions lists change, balances change, mandates change. Release itself is the anchor event reconciliation ties back to: who released, when, under what limit and approval, with what liquidity confirmation, carrying which references. And release feeds the queue honestly. A released payment with full liquidity coverage proceeds to immediate settlement; a released payment without it waits in the queue with visible status, an owner, and an expected funding time. Processing must never label a queued payment "sent" to make a report look tidy. The words it chooses here become the customer promise in Section 6 and the investigation starting point in Section 8.
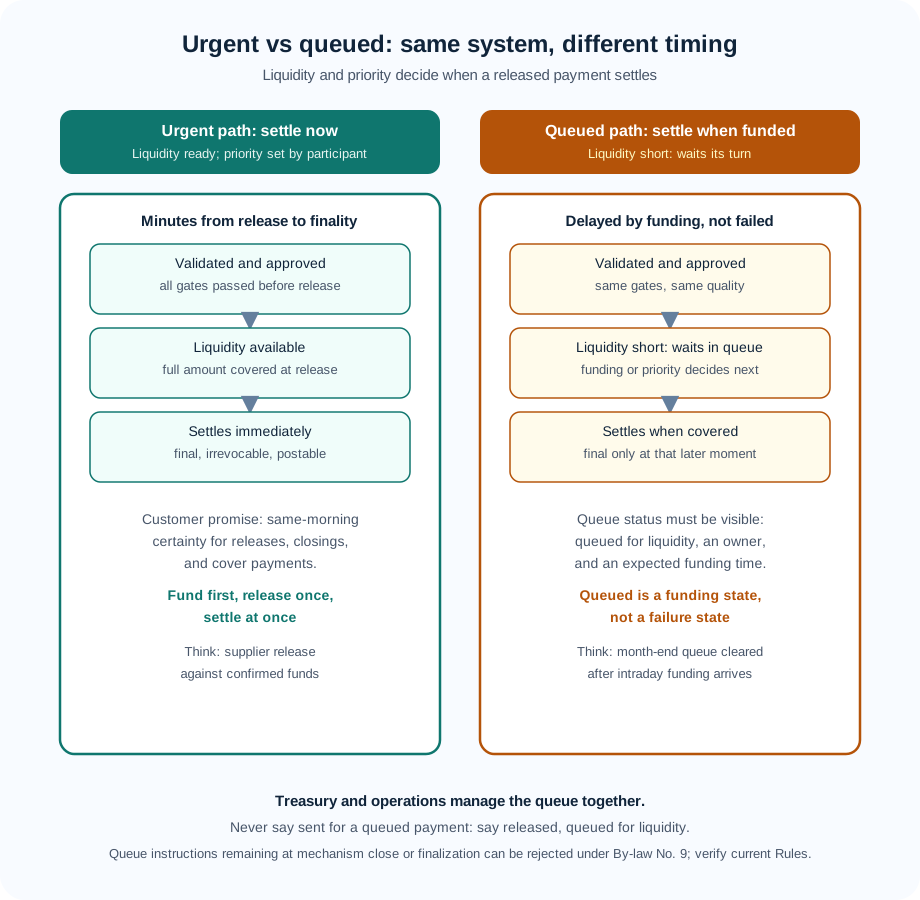
Trace any payment you handle through both paths above and ask which one it took and why.
4. Clearing, settlement and finality — the RTGS core
This is the section the whole chapter exists for, and it repays slow reading, because everyday language collapses five distinct events into words like "cleared," "completed," or "done." In Lynx operations, message acceptance, queueing, settlement, posting, and availability each have their own meaning, timestamp, and proof — and finality is a legal and operational state attached to exactly one of them. Confusing these events creates wrong customer promises, wrong liquidity decisions, wrong controls, and wrong incident responses. This section defines each event, plants the finality boundary precisely, and separates the three finalities that bankers most often merge.
Start with the mechanics in order. Message acceptance is Lynx admitting the payment instruction into its processing: the message is well-formed, the sender is entitled to send, and the instruction enters the settlement pipeline. Acceptance evidence answers: what was received, from whom, when, carrying which references. Acceptance is not settlement. A payment can be accepted and still wait — for liquidity, for its priority turn, for the operating day's mechanics — and anyone who tells a customer "Lynx has it, so it's settled" has spent certainty the bank does not yet own.
Queueing is the ordered wait between acceptance and settlement. Funded payments pass through in moments; payments short of settlement balance wait until funding arrives or priority management changes their turn. Queueing is normal RTGS behaviour, not failure — liquidity is finite and payments do not arrive in funded order. The discipline is visibility: each queued payment carries a status, an owner, and a reason, managed jointly by treasury and operations. A queued payment is still revocable-side: it has not crossed the line.
Settlement is the event itself: Lynx transfers the amount from the sending participant's Lynx account to the receiving participant's Lynx account for the selected settlement mechanism and makes the corresponding account entries, payment by payment, in central-bank money. There is no deferred retail-batch settlement; however, the LSM can recycle liquidity and use payment offsetting to settle queued obligations simultaneously under Lynx's rules. Each obligation still receives its own settlement outcome and confirmation. The settlement evidence is the Lynx confirmation with the system-generated PCRN, applicable message references, and the participant's settlement-account records. Do not turn this into a customer-visible promise of identical timestamps or direct access to the Bank of Canada ledger.
Posting moves the value into customer and internal accounts: the payer account is debited, the beneficiary account is credited, fees are applied, and settlement-account entries are mirrored in participant books. Posting follows settlement and references it; operations posts from settlement proof, never from acceptance or a queue position. Availability is when the payment is finally and irrevocably made available to the payee. Under By-law No. 9 section 36, once the obligation is settled and the receiving participant has the payment message and PCRN, the receiving participant must make the payment available by the end of the payments processing cycle, and as soon as feasible when the payee reasonably requests it before cycle end. Credit to the payee account, lawful application against the payee's debt, or other access can constitute availability. Indirect processing, incomplete information, or lawful compliance action can still affect the customer experience; do not describe availability as an unlimited discretionary hold policy.
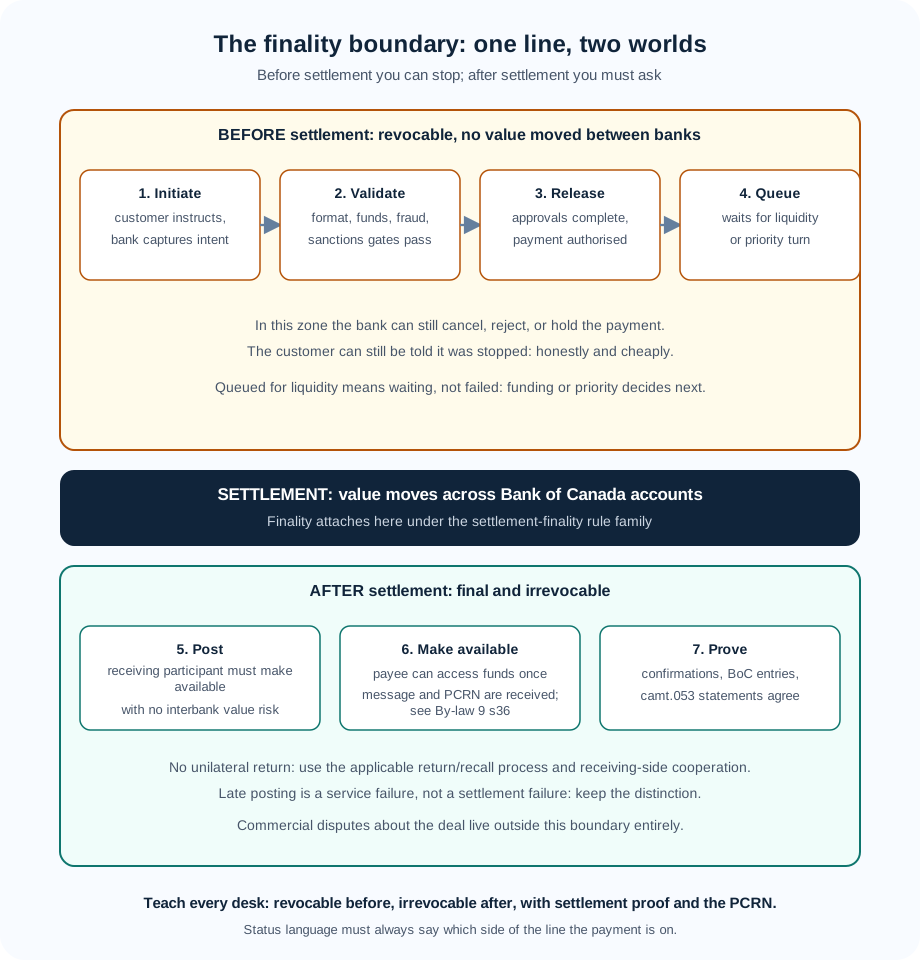
Finality is the point after which the payment cannot be unwound unilaterally under the system's rules — and in Lynx it attaches at settlement. Study that sentence, because everything else in the chapter is commentary on it. Before the boundary, the sending bank can cancel, reject, or hold; the customer can be told "stopped" honestly and cheaply. After the boundary, the sender alone cannot pull value back: no unilateral return exists, no technical recall button reverses central-bank money, and no amount of urgency reopens the entry. Recovery after settlement uses the applicable Lynx return/recall process and the receiving side's cooperation; it is a new, linked message referencing the original, not a unilateral unwind. A bank may make a separate customer-ledger correction under its own authority, but that is not a Lynx reversal. Finality is therefore not a feeling of confidence. It is a rule-state with a timestamp, and the timestamp is the whole product.
Functionally, Lynx By-law No. 9 sections 32–33 and the current Lynx Rule 10 (Finality and return) establish this boundary: settled payment obligations are final and irrevocable as between participants under the system. This chapter states that functionally and goes no further; it does not quote, paraphrase, or interpret legal text. When your procedures, disclosures, or customer agreements need the exact words, go to the authoritative rulebook through Section 12 and have legal confirm the current version. What operations must internalise is the functional consequence: at the settlement timestamp, the interbank risk on that payment ends. The receiving participant holds central-bank value. The sending participant cannot unilaterally reclaim it. Every control, every promise, and every recovery path in this chapter is designed around that consequence.
End-of-cycle procedures close the operating day at the same functional level. Each Lynx cycle ends with defined close-out mechanics: settlement mechanisms close, settlement positions and intraday-loan obligations are addressed, and participants receive the records needed to reconcile. Under By-law No. 9, instructions still in a settlement queue when that mechanism closes, or in conditional release when the finalization window begins, are rejected. The Bank of Canada overview describes Settlement Window 1 as 12:30 a.m.–6:00 p.m., Settlement Window 2 as 6:00–6:30 p.m., and finalization through 7:00 p.m.; treat those published times as operational reference points and verify the current Rules and schedule before relying on them. The close proves terminal states and evidence, not that every accepted instruction settled. A cycle that closes dirty, with payments in unknown states, is an incident regardless of what any screen says.
Now the distinction the task demands and the industry most needs: the three finalities. Settlement finality belongs to the system and the participants: the interbank leg is discharged in central-bank money and will not be unwound unilaterally. Its owner is the Lynx rulebook; its timestamp is the settlement moment; its proof is the confirmation plus the Bank of Canada entries. Beneficiary availability belongs to the receiving bank and the beneficiary: the funds are posted and usable in the beneficiary's account. Its owner is the receiving participant under By-law No. 9 section 36 and its posting/availability controls; its timestamp follows settlement and depends on the payment message, PCRN, indirect route, and lawful processing; its proof is the credit or access record and the account itself. Underlying commercial finality belongs to the contract between the commercial parties: the invoice is satisfied, the goods are accepted, the closing is registered, the dispute rights are exhausted. Its owner is the agreement and the law governing it; its timestamp may be days after settlement; its proof is receipts, releases, registrations, and signatures that no payment system produces.
These three are independent variables sharing one word. Settlement without availability is the beneficiary staring at an unchanged balance at 10:05 for a payment settled at 10:02. Availability without commercial finality is the supplier with spendable funds who still disputes the invoice. Agreement without settlement is the handshake awaiting the wire. Every status and advice should name which finality it means: "settled in Lynx at 10:02, expected in the beneficiary account by noon" is banking; "settled" alone is a coin toss.
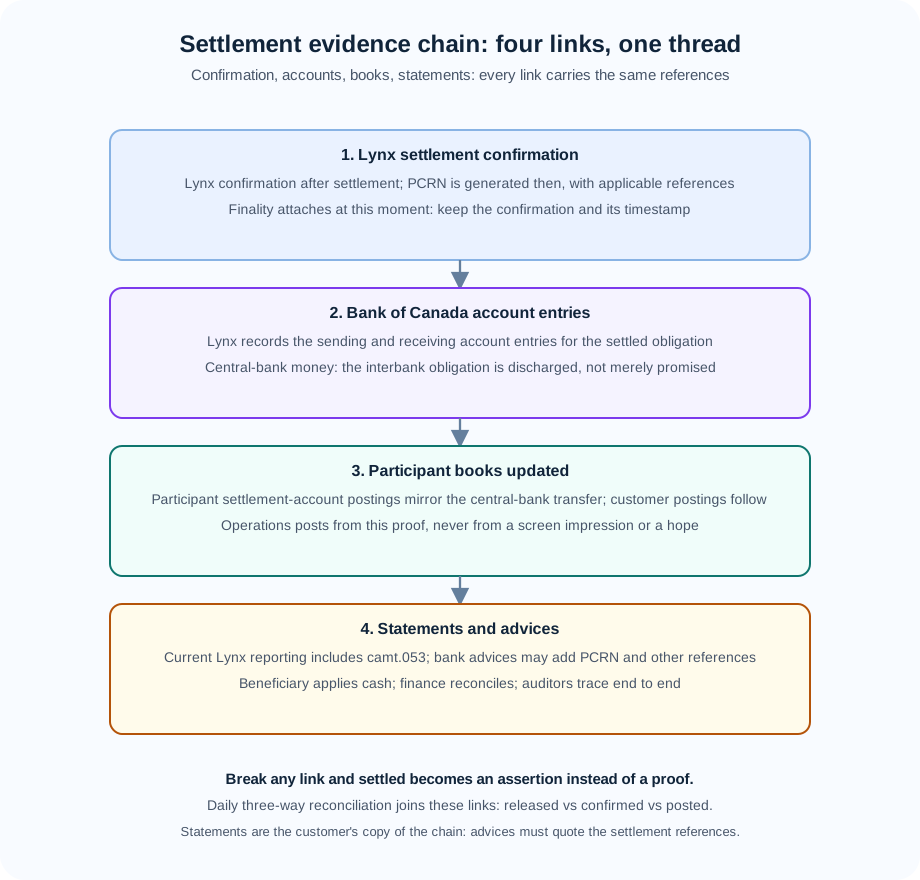
The evidence chain above proves all of this on demand: advice quoting the UETR, camt.053 line, participant posting, participant settlement-account records (and Bank of Canada records where available), Lynx confirmation with timestamp. Five minutes of joined evidence ends arguments that five days of assertion never will.
5. Data, identifiers, messages and references
Settlement is a data problem wearing money's clothes. The value moves in milliseconds; what determines whether anyone can prove it, post it, reconcile it, or recover from its errors is the data that travelled with it and survived intact. This section introduces the Lynx data layer at lifecycle level — what travels, what identifies, how the ISO 20022 messages differ in purpose, and why reference preservation is the difference between straight-through proof and manual archaeology.
Start with the three data jobs, because each fails differently. Routing data gets the instruction to the right participant and account: beneficiary agent identification, settlement path, and the customer account detail the receiving participant will post to. A routing failure on an irrevocable rail is uniquely painful — value settled finally to the wrong participant — so routing validation deserves the deepest checks in the bank: directory freshness, participant reachability on the intended date, beneficiary-account structural checks, and confirmation disciplines for new or changed destinations. Business data proves the obligation and lets the beneficiary apply the money: amount, currency, value date, remittance detail such as invoice numbers, and charge allocation. Rich ISO 20022 remittance is Lynx's quiet advantage over legacy formats: invoice references that travel with the payment let the beneficiary's receivables team apply cash without calling anyone. Control data lets banks and investigators track and reconcile: message identifiers, end-to-end references, the UETR that survives correspondent chains, the PCRN generated by Lynx after settlement and used with applicable return and investigation references, and handoff timestamps at every boundary. A payment missing any of the three can be settled yet useless — delivered but unappliable, or posted but untraceable.
At minimum, every Lynx payment needs three identities that survive from initiation to statement: the bank's own instruction reference created at initiation, the network identifiers assigned through processing and settlement, and an end-to-end reference both commercial parties can quote to each other without involving either bank. For wires and cross-border chains where the message profile uses it, the UETR is an end-to-end thread — generated once, carried in its dedicated element, and preserved in confirmations and investigations. Do not assume that every domestic Lynx customer reference is a UETR. For Canadian mechanics, the PCRN is the system-generated settlement confirmation reference. It is available only after a payment settles through Lynx and can be requested from the financial institution; use it with the payment message references in returns and investigations, including pacs.004 where the current specification requires linkage. The rule is absolute and worth enforcing with automated checks: references created at initiation must survive enrichment, conversion, queueing, settlement, posting, and reporting. Any transformation that rewrites the end-to-end reference breaks tracking, investigations, and reconciliation at once — and on a finally-settled payment, the break cannot be fixed by returning and re-sending.
Messages and formats differ by purpose, and each Lynx message family earns its place. Customer and interbank credit transfers travel as pacs.008 and pacs.009 (core and cover variants) over the participant messaging path. The full payment message remains with the messaging service provider and participants; Lynx receives the partial settlement copy needed for system processing, including the sending and receiving participants, message type, settlement mechanism, amount, value date and currency, not customer account numbers or remittance information. pacs.004 handles payment returns as a new message referencing the original under the current Lynx specification. Lynx's current reporting page lists camt.053 for the bank-to-customer statement. camt.052, camt.053 and camt.054 also appear in Payments Canada's corporate-to-bank guidance, so do not imply that every camt message is a Lynx settlement-system output.
Three practices separate strong settlement operations from fragile ones. Validate at the boundary in the rail's own terms — schema, character sets, and field rules for MX, with realistic Canadian content including accented Quebec names, long legal-entity titles, and structured remittance — and prove that validations round-trip references without truncation or rewriting. Carry screening and compliance data with the payment rather than beside it, so holds, dispositions, and reporting reference the exact payment object the settlement engine acted on. And design remittance for the beneficiary's reconciliation, not the sender's convenience: a supplier wire carrying invoice numbers and the sender's end-to-end reference auto-applies on receipt; a CAD 4.2 million payment with "payment" in the reference field becomes a manual investigation at the receiving bank, with the funds settled, available, and useless until someone makes phone calls. The money moved; the business purpose did not. That gap — settled but unapplied — is the most common form of successful payment failure, and reference discipline is its prevention.
Take a Montreal-to-Calgary supplier wire for CAD 850,000 with invoice references INV-4471 and INV-4472. At initiation the channel creates reference MTL-2026-08841 and the bank generates a UETR. Enrichment into the pacs.008 must carry all three — instruction reference, UETR, invoice numbers in structured remittance — and no PCRN yet: Lynx generates the PCRN only after settlement. Confirmation then supplies the PCRN and applicable references; postings and both advices quote MTL-2026-08841; the camt.053 line closes corporate reconciliation automatically. Drop INV-4472 in mapping and the payment still settles finally — yet the beneficiary cannot apply half of it, and the resulting investigation costs more than the payment's margin. Same settlement, opposite outcome. Teach this to every developer who touches format mapping: they hold the settlement's provability in their hands.
6. Rules, service levels, operating day and customer impact
Customers experience settlement rules as promises: "it will be there this morning," "same-day if you send by when," "you can cancel until…," "it cannot be reversed after…." Operations experiences the same rules as constraints: the operating day, release cutoffs, queue behaviour under liquidity stress, end-of-cycle close, and staffing through posting and investigation windows. This section connects the two views so that product, operations, treasury, and customer-facing teams describe the same reality — and so that no promise outruns the settlement behind it.
Rules come in layers, and quoting one layer while forgetting the others manufactures the misses customers remember. System rules — the Lynx by-law, rules, and procedures — define what the network accepts, when, in what format, with what finality, and with what return and recovery rights. Legal and supervisory overlays define what banks must do regardless of the network: screen, report, safeguard, disclose, and treat customers fairly. Bank policy translates both into the customer's lived experience: channel cutoffs, fees, limits, approval thresholds, availability timing, and status language. A product page that says "wires settle in real time" without "our release cutoff is mid-afternoon and your payment needs dual approval plus liquidity confirmation" sells a settlement the bank may not deliver that day. Publish the most restrictive applicable constraint as the customer cutoff, and publish the finality caveat — irrevocable after settlement — wherever a wire can be instructed.
The operating day and cutoffs turn settlement mechanics into dates and clocks. Lynx operates on a defined business-day calendar with published closure schedules; the payment's value date, queue behaviour, and cycle membership all hang off that calendar. Within the day, a chain of cutoffs decides each payment's fate: the channel cutoff for customer submission, the internal cutoff for validation and approval completion, the release cutoff for entry into Lynx, and the cycle close that sweeps remaining states into a clean end. Miss the institution or system cutoff and the request may be held or processed on the next business day, subject to the bank's policy and the current Lynx schedule. Do not promise a new value date or same-cycle settlement until the bank has actually accepted and released the payment. This chapter states no clock-times, because times belong to the official calendar and each bank's published schedule; it states the discipline instead. Every promise needs a cutoff and a fallback: "submit by our published time for same-cycle settlement; after that, next cycle with value date X, and here is what we tell your beneficiary." Recovery from a miss means re-dating, re-funding, re-communicating, and re-reconciling — because one cutoff was treated as advisory.
Service levels bundle speed, certainty, reach, transparency, and recoverability into the product the customer actually buys. Lynx offers speed plus certainty — per-payment finality in central-bank money — at higher cost in fees and intraday liquidity than batch. That bundle suits obligations where doubt is expensive: supplier releases, closings, covers, margin calls, interbank obligations. It does not suit everything: routine payroll, recurring collections, and low-value transfers pay the liquidity and fee cost without needing the certainty, and forcing them through RTGS is a design error the lifecycle makes visible early. Present trade-offs, never rankings. A same-day batch promise with return rights is not an inferior version of a wire; it is a different product with a different finality bargain, and pricing, disclosures, and support scripts must reflect that. The planned Real-Time Rail, where it appears in conversation, must never be sold as a current service level. This chapter makes no claim that RTR is in production; current capability, launch date, access model and rules must be verified on Payments Canada's RTR pages before use. What a bank can promise today is what its current channel and Lynx arrangement can actually settle.
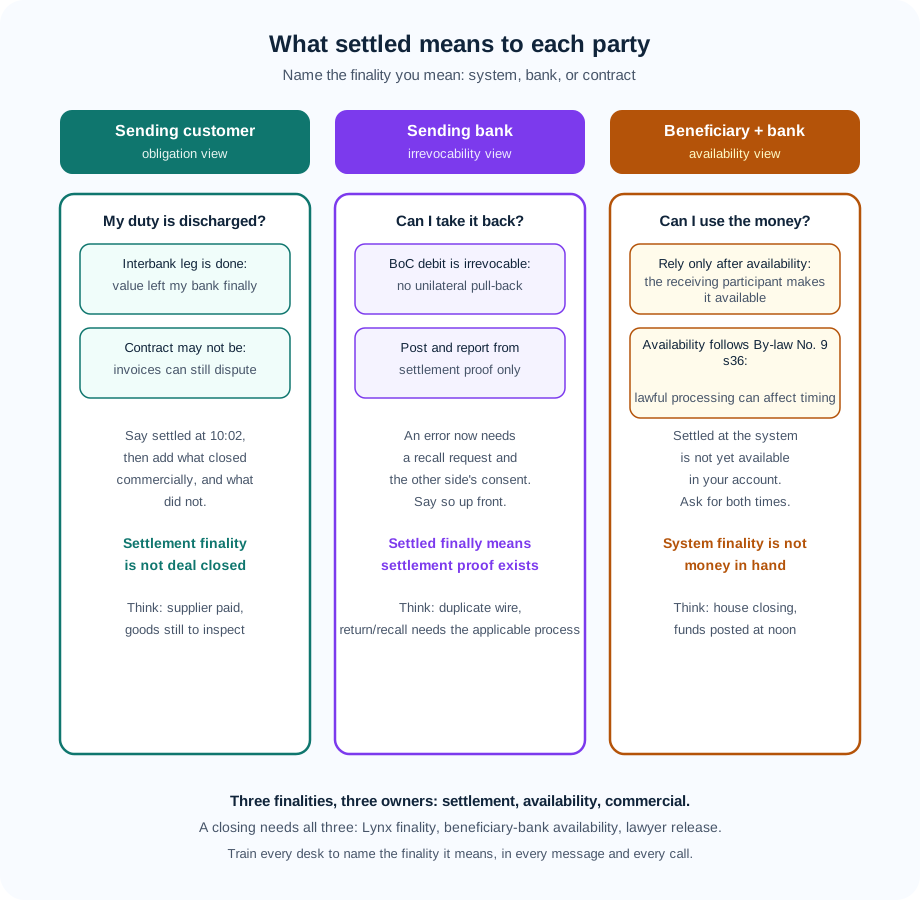
The diagram above is a daily tool, not decoration. Use it to audit every customer-facing sentence your bank publishes about wires. For each claim — "settled," "complete," "guaranteed," "irrevocable," "available" — ask which of the three finalities it asserts and whether the bank controls that finality. "Settled in Lynx at 10:02" asserts settlement finality: true when the confirmation and account entries exist, and the bank can prove it. "Available to your supplier this morning" asserts beneficiary availability: true only if the receiving bank has posted and released, which the sending bank cannot guarantee — so phrase it as an expectation with a confirmation step, not a warranty. "Your deal is closed" asserts commercial finality: never the bank's to declare. Four practices follow. Promise only the posting and availability the arrangement actually supports, with the irrevocability caveat stated wherever release is possible. Give every promise a cutoff and a fallback. Communicate status in lifecycle states the other bank can verify — released, queued for liquidity, settled at HH:MM with reference R, posted, available — never "processing." And staff through posting, return-request, and investigation windows, not just release hours, because customer anxiety peaks after settlement, not before.
Make it concrete: a supplier release needed Tuesday morning in Calgary, instructed Monday from Montreal — customer approval, bank channel cutoff, validation plus screening plus dual approval, liquidity confirmed, release with priority set, settlement confirmation, beneficiary posting Monday afternoon, availability per policy, advices quoting UETR and end-to-end reference, reconciliation closed with proof joined. Each handoff needs a named owner and a clock, and the customer promise is the most restrictive constraint in that chain. Publish the chain alongside the promise so a late instruction triggers the documented fallback, not a negotiation about whether the cutoff was real.
7. Fraud, compliance and operational controls
Controls on an irrevocable rail are gates or they are theatre. A check that completes after settlement can inform, report, and console, but it cannot prevent — and prevention is the only control that matters when value cannot be pulled back. This section maps fraud, sanctions, AML, and operational controls onto the lifecycle relative to the finality boundary, so that designers put each check where it can still stop, hold, or inform, and so that auditors can trace each decision to evidence.
Fraud controls concentrate before release, without exception. Pre-release work starts with authentication strength matched to channel and amount — irrevocable value instructed online deserves stronger binding than a balance inquiry, and business channels need approval workflows that survive absent approvers and end-of-day pressure. Device and behavioural signals, payee verification and callback discipline for new or changed beneficiary instructions, velocity and anomaly scoring against the customer's history, and dual preparation-plus-approval for business payments all belong before the release signature. Authorised-push scams and redirection emails exploit exactly this window: the fraudster does not break cryptography, they persuade the legitimate user to instruct correctly-formed payment to the wrong beneficiary — which every downstream check will then wave through, because the instruction is valid and only the intent is poisoned. Confirmation of new payees through trusted channels, cooling-off discipline for changed instructions above threshold, and amount-sensitive step-up authentication are the defences, and they only work before release. A fraud score arriving after settlement is a report, not a control. Scores must resolve to release, hold, step-up, or reject while stopping is still possible.
Sanctions, AML, and travel-rule controls gate initiation through release and shadow the payment downstream. Screening must complete — including false-positive disposition with recorded rationale — before a wire releases, because a sanctions breach in a finally-settled payment is a violation with no technical undo. Completeness of originator and beneficiary data is itself a control: truncated party data that "passes" screening faster creates the exposure the control was meant to prevent, and rich ISO 20022 data should be treated as screening fuel, not formatting overhead. Holds need honest customer status with an owner and a clock, and lawful next steps that avoid tipping off where the regime requires it. Record every disposition against the payment object: who decided, on what data, when, with what outcome. An auditor — or a regulator — reconstructing a released wire will ask for exactly that record, and "the system passed it" is not an answer.
Operational controls prevent most value-weighted loss: duplicates, balance and limit enforcement, mandate verification, cutoff enforcement, reference validation, release authority, and segregation of preparation, approval, and release. Each must produce a decision record. A duplicate check that silently drops the second submission prevents double-pay but creates a reconciliation mystery and a furious customer; the same check with a clear duplicate-reject advice prevents both the loss and the mystery. Balance and limit checks must run against the gross amount at release time, not against yesterday's balance or a netted assumption carried over from batch habits. Cutoff enforcement must be systemic — a release button that works after the cutoff manufactures next-cycle payments wearing same-day promises. Reference validation must confirm the UETR, PCRN, and end-to-end identification are present and well-formed before the message leaves, because a settled payment with broken references is provable only through manual archaeology.
Placement summary: initiation owns authentication, authority, beneficiary confirmation, and intent clarity. Validation owns format, mandate, funds, duplicate, reachability, fraud, and sanctions gates with explicit outcomes. Processing owns enrichment, route choice, cutoff and liquidity checks, priority, and release authority. Settlement and queueing own acceptance monitoring, queue visibility, and the funding partnership. Posting owns account integrity. Reporting and reconciliation own completeness proof and feedback into upstream rules. State each control's position relative to finality in its first sentence — before the boundary it prevents, after it merely records.
8. Exceptions, investigations and recovery
No settlement teaching is complete without its failure vocabulary, because the words banks use after settlement determine whether recovery is fast, lawful, and reconcilable — or slow, disputed, and double-counted. Lynx operations use a smaller set of terms than batch, and the set is smaller for exactly one reason: finality removed the easy options. This section defines each available path, places it relative to the boundary, and enforces the reference discipline that keeps recovery from becoming a second incident.
A reject happens before the payment leaves the acceptance boundary — the sending bank rejects an invalid instruction, Lynx refuses a malformed message, validation stops an unscreened or unauthorised item. Nothing settled, nothing irrevocable, nothing to recover. Respond with a clear reject advice and reason codes enabling repair, keep the rejection in the instruction's history, and route the cause back into initiation rules. Rejects are the cheapest exceptions and should be the most common: a Lynx operation with few rejects and frequent post-settlement problems has its gates in the wrong place.
A return request after settlement is governed by the current Lynx Rule 10 and By-law No. 9, not by a generic recall button. For an error in the original payment message, Rule 10 section 5 lets the sending participant request return; if the receiving participant has not yet made the amount available to the payee, it may return it and may ask for an indemnity. Rule 10 also requires or permits returns for specified receiving-side errors, account restrictions, legal or court restrictions, foreign-currency accounts and payee requests. Once funds have been made available, recovery may require an agreement or another remedy under general law. A return is a new pacs.004 message linked to the original, not a unilateral unwind. State the outcome honestly: settlement was final, the return path has been invoked, and recovery is not guaranteed.
Do not call a post-settlement Lynx return a reversal. A pacs.004 return is a new, linked payment message governed by the current Lynx specification and applicable Rule 10 process; it does not erase the original settlement. Any bank-side customer-account correction is a separate ledger event with authority, reason, and an immutable pointer to the original. Auditors must be able to trace both events.
An investigation is the case around uncertainty: where is the payment, what state is it in, who holds it, what is the next step. Preserve the original identity throughout — UETR, PCRN, instruction reference — and accumulate evidence in one case with one owner: initiation record, validation dispositions, release authority, acceptance, queue history, settlement confirmation with timestamp, participant settlement-account records, posting records, advices. The most expensive investigation failure is re-payment on pressure: a "replacement" released while the original sits queued for liquidity, held for screening, or settled but unposted creates two live payments where one problem existed. Trace first, classify second — rejected, queued, settled-and-posted, settled-but-unapplied, recall-pending — and act with linkage third. And communicate in states the other participant can verify: "released, queued for liquidity," "settled HH:MM reference R," "recall requested, awaiting response," never "we're looking into it" as a final answer.
Two recovery principles close the section. First, post-settlement recovery is a negotiation conducted with evidence, not an operation performed with buttons. The bank that arrives at the receiving participant with the full joined chain — confirmation, entries, postings, references, timeline — gets cooperation faster than the bank that arrives with urgency and adjectives. Build the evidence pack as a one-click product of your payment store, because recall cases age in hours and goodwill. Second, never let recovery create a second original. Link every recovery action to the original case, hold replacements until the original's state is proven, and book any urgent customer remediation explicitly as goodwill — not as a second payment for the same obligation.
9. Posting, accounting, liquidity, reporting and reconciliation
Settlement takes milliseconds; proof takes all day. Stages 6 through 8 are where a finally-settled payment becomes posted value, funded reality, reported information, and reconciled truth. Customers judge the bank on posting and reporting; finance judges it on accounting and reconciliation; treasury judges it on liquidity. This section treats the four as one assurance chain: post correctly, account completely, fund sufficiently, report clearly, and prove it all balanced — per payment, not per batch.
Posting applies settled value to accounts: payer debit, beneficiary credit, fees, suspense for items awaiting application, settlement-account entries mirroring the Bank of Canada movements. Discipline starts with direction: post from settlement proof, in settlement order, with idempotency at the posting engine so that a retried confirmation can never double-post. Value-dating must reflect the settlement date honestly — a payment settled in one cycle must not wear another cycle's date to flatter a report. Memo-versus-hard-post hygiene matters where customer channels show pending states: a memo that looks like a debit without the hard post behind it, or a beneficiary credit shown before the posting engine has acted, manufactures the exact confusion Section 6 forbids. Suspense discipline is strictest on this rail: a settled-but-unapplied wire sitting in suspense is final value nobody owns operationally, so age suspense in hours and days with named owners, not in months. For on-us items posting is the whole story; for Lynx items posting must reference the clearing and settlement evidence it reflects, reference by reference.
Accounting translates postings into ledgers the bank controls against: settlement accounts at the Bank of Canada, customer deposit liabilities, fee income, suspense, and interbank positions. The telltale of weakness is ledgers that each balance but disagree with each other — the settlement account says value left, the customer account says it did not, and month-end becomes archaeology. Strong accounting drives double-entry from the same lifecycle records operations uses: one release, one acceptance, one settlement proof, one posting, one ledger impact. Finance and operations then share one truth and month-end confirms rather than discovers. On Lynx the accounting has a per-payment grain that batch accountants find unfamiliar: each settlement is its own event with its own timestamp and references, so intraday positions move payment by payment and the ledger must keep pace. Design the chart of accounts and the posting rules for that grain from the start; bolting per-payment accounting onto a batch-shaped ledger produces the breaks reconciliation will spend every morning explaining.
Liquidity funds gross settlement when the timetable demands it, and on this rail it is a release constraint, not a back-office concern. Each Lynx payment needs its full amount covered — sufficient settlement balance or available intraday credit — at the moment it is to settle, or it queues. That single fact reorganises the bank's daily partnership: treasury forecasts and positions liquidity across the operating day, operations sequences releases and sets priorities against the forecast, and both watch the queue together as conditions change. Month-end, tax dates, and large corporate flows concentrate demand; foreign-exchange settlement windows and interbank obligations add their own peaks. A validated, approved payment that cannot be funded cannot settle, and the bank must show "queued for liquidity" honestly — with owner and expected funding time — rather than "sent." Three liquidity disciplines matter most. Confirm coverage before release for urgent payments rather than discovering the shortfall in the queue. Prioritise deliberately: time-critical customer wires and systemic obligations first, routine value when funding allows, with the priority policy written down and the exceptions logged. And manage the end of the day as a joint treasury-operations drill: which queued payments must settle this cycle, what funding closes them, who authorises it, and what the customer is told about each one. Liquidity is the common reason a released Lynx payment waits, but the settlement mechanism, its queue rules, participant availability, and cut-off/finalization state also matter. Every non-terminal status needs a reason, owner, and customer-safe explanation; do not relabel a rejected-at-close or conditional-release item as a liquidity queue.
Reporting turns settlement events into customer-usable information: payer debit advices with the settlement timestamp, beneficiary credit advices quoting UETR and end-to-end reference, corporate statements and camt.053 or other bank feeds keyed to original references, settlement-account activity for treasury, and exception advices for recalls and investigations. Preserve references end to end, state each date precisely — release, acceptance, settlement, posting, availability — rather than one merged "date," and explain exceptions with reason plus next step rather than code alone. Corporate customers judge a bank on this layer: a treasurer receiving fifty wires needs each one auto-applied against payables from the statement feed, not fifty phone calls. Design advices for the beneficiary's receivables team, who never met your payment hub and should never need to: amount, value date, sender identity, invoice references from remittance, and the reference to quote if anything looks wrong.
Reconciliation proves the chain, and on RTGS it runs at payment grain on an intraday heartbeat: three-way — (A) instructed and released, versus (B) Lynx acceptance and settlement evidence, versus (C) participant settlement-account reports and books; Bank of Canada records are supporting evidence where available. Instruction-versus-acceptance breaks belong to channels, hubs, and gateways: released but never accepted means a gateway, format, or entitlement problem. Acceptance-versus-settlement breaks belong to settlement operations and treasury: accepted but unsettled means queued, held, or caught by cycle mechanics — each with a legitimate state that must be visible, not a mystery. Instruction-versus-participant-books breaks belong to posting, finance, and reconciliation: settled but unposted means a posting-engine or mapping problem with final value at stake. Run it intraday for Lynx — end-of-day is too late for irrevocable value — match on reference, amount, date, and status together, age breaks in hours with owners, and feed repeat causes back into validation and routing rules. A balanced reconciliation can still contain unapplied obligations — every item matched but one beneficiary credit sitting in suspense — so track status semantics, not just totals. And close each cycle with the terminal-state proof from Section 4: every accepted payment for the cycle in a known final state, settled or otherwise properly disposed, with evidence joined. That close is what end-of-cycle procedures exist to produce.
A short case shows the model under stress. A customer releases three wires totalling CAD 9.4 million: supplier, tax, interbank cover. Midday reconciliation reports released three, accepted three, settled two with confirmations and matching participant settlement-account records; the third queued for liquidity with treasury owning funding due within the hour; postings show two debits and two credits, correctly nothing for the queued payment. The message — "released, queued for liquidity, expected funded within the hour" — went to the customer before day-end, not after. When funding arrives, the third confirmation joins the same chain. That is RTGS reconciliation as a product feature: per payment, per moment, provable.
10. Bank implementation, testing and resilience
Understanding settlement is necessary but not sufficient; a bank must also build it, prove it, and keep it running through failures. This section translates the settlement model into implementation scope, testing discipline, and resilience expectations that product owners, engineers, and operations managers can plan against. It stays at settlement level — message field detail belongs to the message chapters — and focuses on the decisions that determine whether a Lynx operation is safe to trust with irrevocable value.
Implementation starts with architecture that respects the finality boundary: channels, payment hub, core banking, the Lynx gateway, fraud and sanctions services, reference data, liquidity and treasury feeds, accounting and reporting, reconciliation and case management — exchanging reference-keyed events rather than duplicating decisions. Common errors cluster around the boundary. Validating only in the channel while the hub trusts blindly. Screening at initiation so warehoused instructions age past list updates before release — re-screen at release, always. Converting formats while dropping the UETR, PCRN, or end-to-end reference. Posting from acceptance or queue status instead of settlement evidence. Showing customers "sent" for released-but-queued payments. Treating indirect access or vendor gateways as transferred accountability — outsourcing the work never outsources the responsibility for validation, funding, monitoring, and customer answers, which must be contractual, staffed, and evidenced. And building a batch-shaped payment object for per-payment settlement: the bank needs a canonical payment record carrying the instruction, all network identifiers, enrichment and disposition history, routing decisions with rule citations, queue history with timestamps, settlement proof with timestamp, posting records, and exception linkages — one object per payment, from initiation to archive.
Name the operational risks explicitly so they can be owned. Duplicate-release risk: a retried file or double-clicked wire pays twice, with recovery only through cooperation — prevent with idempotency from channel through gateway. Reference-loss risk: truncated remittance or rewritten identifiers create settled-but-unapplied value and investigation queues. Liquidity-shortfall risk: queued payments miss supplier deadlines and closings while the customer screen says "sent." Cutoff-miss risk: a late instruction re-dates value and triggers compensation claims. Fraud-acceptance risk: authorised-push scams and redirection emails exploit validation gaps before irrevocable release. Posting-integrity risk: double-posts on retried confirmations, wrong-account credits, unaged suspense silently misstate positions. Evidence-gap risk: a silent handoff between hub and gateway leaves reconciliation with nothing to join. Availability-confusion risk: customers and even staff read settlement confirmations as spendable funds. Third-party risk: a vendor gateway or screening utility fails and the bank discovers accountability never transferred. Calendar risk: holidays and daylight boundaries shift value dates the promise did not anticipate. Assign each risk a control owner, a detection metric, and a tested playbook — that register is the practical output of this section.
The bank's data and format work needs versioned mappings tested with realistic Canadian content — accented Quebec names, long legal-entity titles, structured remittance with invoice detail — proven to round-trip the UETR and end-to-end references, while treating PCRN as a post-settlement Lynx output without truncation across every transformation the payment undergoes, with customer communication correct in both English and French where the bank serves both languages.
Testing must prove settlement behaviour, not just connectivity: gates that reject cleanly; routing correctness at cutoff boundaries; queueing under constrained liquidity with honest status; posting with no double-posts and correct value dates; reporting joined to original references; reconciliation closure at payment grain; full exception journeys from reject to investigation evidence pack. Inject failures — gateway outage, funding shortfall, posting delay, stale reference data, duplicate storms. Certification proves message exchange; lifecycle testing proves safe operation of irrevocable settlement.
Resilience assumes components fail and requires graceful degradation without losing or duplicating finally-settled value: duplicate-safe retry everywhere, warehoused work surviving outages with triggers and re-screening intact, visible queue intervention with treasury authority paths, re-driveable submission without re-creating obligations, pausable posting engines that prove no gap or overlap on restart, reporting that distinguishes delayed from missing, and reconciliation that maps the outage's footprint payment by payment and guides ordered catch-up. Add people and process: coverage through settlement, posting, and investigation windows — customer anxiety peaks after the release burst, not during it; incident communication in lifecycle states the other participant can verify ("queued for liquidity, funding expected within the hour," "settled HH:MM reference R, posting delayed, value date preserved"); practiced fallback per scenario including gateway, liquidity-feed, and posting-engine loss. Every scenario must answer three questions for each in-flight payment: which side of the finality line is it on, what is its next legitimate state, and what should the customer be told right now? If answering needs forensics, resilience is not built.
11. Practical Canadian end-to-end examples
Three fictional stories carry the chapter's lessons into situations you will recognise. Each is invented for teaching, with simplified figures; none describes a real payment, real bank, or real customer. Read each one twice: once for the story, once for the control it exists to install.
Example (fictional): the Calgary supplier release. A Toronto equipment manufacturer owes a Calgary supplier CAD 4.2 million, and the supply agreement releases a steel shipment against confirmed, irrevocable funds by Tuesday noon Calgary time. The manufacturer's treasury team instructs the payment through its bank's host-to-host channel Monday morning, quoting invoice references ST-8814 and ST-8815 with its end-to-end reference TOR-2026-11402. The bank validates in full — format, dual approval, balance for the gross amount, duplicate check against recent history, beneficiary confirmation because the supplier's instructions changed last quarter and were verified by callback — screens with disposition recorded, confirms liquidity, and releases the pacs.008 with priority set for a time-critical commercial payment. Lynx accepts within moments and settles: confirmation echoes the UETR, the participant settlement-account records show the central-bank transfer, finality attaches. The receiving participant posts the supplier's account Monday afternoon, availability follows By-law No. 9 section 36 and applicable Rule 10 exceptions, and both commercial parties receive advices quoting TOR-2026-11402 with the invoice references intact — so the supplier's receivables team applies cash automatically and releases the shipment Tuesday morning. Treasury reconciles intraday: released one, accepted one, settled one, posted one, references joined. The control lesson: urgency translated into the correct rail, validation matched to irrevocability, and references preserved so settlement becomes applied cash.
Example (fictional): the month-end queue. A Vancouver forestry company pays a CAD 900,000 interbank cover through its bank on a heavy month-end morning when the bank's liquidity is stretched across dozens of large releases. Validation passes completely — the instruction is clean, approved, screened, and authorised. But treasury's forecast shows insufficient settlement balance for immediate settlement alongside higher-priority customer closings, so the payment releases into Lynx and queues for liquidity with its priority correctly set below the time-critical items. Here the bank earns its maturity: operations does not tell the customer "sent." It tells the truth within minutes — "released, queued for liquidity, owned by our treasury desk, expected funded within the hour" — with a case reference and a named contact. Treasury funds intraday, the payment settles with finality attaching at that later moment, posting and advices follow with the settlement timestamp, and reconciliation shows the full honest trail: released 10:14, queued for liquidity, settled 11:02, posted 11:05. The customer, told the truth early, adjusts its downstream timing without panic. The control lesson: queued is a funding state with an owner and a clock, not a failure to hide.
Example (fictional): the duplicate that could not come back. A Montreal distributor's accounts team, working late on a Friday, releases a CAD 150,000 supplier wire and — seeing no confirmation in the inbox it expected — releases the file again "just to be sure." Both instructions are well-formed, both pass validation independently, and Lynx settles both: two confirmations, two settlement-account entry sets, two final and irrevocable payments to the same supplier for the same invoice. Monday brings discovery and dread. There is no unilateral return: the bank cannot pull either payment back. It opens a recall case on the duplicate within the hour, arriving at the receiving participant with the full evidence pack — both confirmations with timestamps, both UETRs, the customer's written confirmation of the error, and a clearly referenced request — and communicates honestly to its customer: "both payments settled finally; we have requested return of the duplicate under case reference R; Rule 10 return has been requested; whether the receiving participant can return it depends on the payment's availability state and applicable rule/general-law path; here is the clock and next step." The supplier and receiving participant cooperate; the return arrives as a linked pacs.004 referencing the original. The control lesson: release locks, duplicate checks, and submission confirmations so users never re-release "just in case."
12. Key takeaways and authoritative references
Twelve sentences carry this chapter into every wire you will ever touch. Real-time gross settlement means each payment obligation settles through Lynx in central-bank money; Lynx is not deferred retail-batch settlement, although its LSM can recycle liquidity and offset queued obligations under the system rules. Settled Lynx payments are final and irrevocable as between participants under the system's settlement-finality rules, stated here functionally; the exact legal text lives in the authoritative rulebook, not in this chapter. Finality attaches at the settlement timestamp — before that line you can stop, after it you must ask. Settlement finality, beneficiary availability, and underlying commercial finality are three independent promises with three owners; never let one word cover all three. Settlement evidence is a four-link chain — Lynx confirmation/PCRN, participant settlement-account record, participant books, and statements/advices — joined by the UETR, PCRN, and end-to-end reference, and any break turns proof into assertion. Queued is a funding state with an owner and a clock, never a failure to hide and never a payment to call "sent." Liquidity is a release constraint: confirm coverage before release, prioritise deliberately, and run treasury-operations funding as a joint intraday drill. Controls prevent only before the boundary — fraud, sanctions, duplicates, limits, approvals — while post-settlement controls report, post, investigate, and pursue an applicable return with evidence. Under FINTRAC guidance, travel-rule and EFT reporting/record obligations also depend on the transaction type and reporting-entity role; do not reduce them to a generic “screen before release” slogan. Recovery after settlement uses the applicable return/recall process or investigation: new messages, cooperation, linkage, one case, one owner. Posting follows settlement proof with idempotency and honest value dates; reconciliation runs intraday at payment grain, three-way, to terminal states every cycle. End-of-cycle procedures close each cycle cleanly: every accepted payment in a known final state with joined evidence. And the bank that deserves irrevocable settlement validates twice, funds deliberately, releases once, reports honestly, and proves everything on demand.
Carry those sentences into the neighbouring message, liquidity, exceptions, and reconciliation chapters — and return to the finality boundary whenever detail threatens to blur it.
Authoritative references — official sources only. Consult the current version of each before relying on it for procedures, disclosures, or customer agreements; this chapter describes rules functionally and these documents govern.
-
Payments Canada — Lynx, Canada's high-value payment system (RTGS model, real-time settlement finality, irrevocable wires, systemic designation, Bank of Canada monetary-policy mechanism): https://www.payments.ca/systems-services/payment-systems/high-value-payment-system-lynx
-
Payments Canada — Lynx ISO 20022 message specifications (current UG2026 pacs.008, pacs.009 core/cover and pacs.004; current Lynx reporting camt.053 and corporate-to-bank guidance): https://www.payments.ca/payment-resources/iso-20022/high-value-payment-system-lynx
-
Payments Canada — Lynx launch announcement, 1 September 2021 (replacement of the Large Value Transfer System; systemic importance): https://www.payments.ca/payments-canada-launches-lynx-canadas-new-high-value-payment-system
-
Bank of Canada — payment systems oversight and designated systems: https://www.bankofcanada.ca/core-functions/payment-systems/
-
Department of Justice Laws Website — Payment Clearing and Settlement Act (S.C. 1996, c. 6, Sch.), the designation and oversight framework: https://laws-lois.justice.gc.ca/eng/acts/P-4.4/
-
Payments Canada — Lynx Rule 10 Finality and return (2026; amended effective July 27, 2026): https://www.payments.ca/sites/default/files/rule_10_finality_and_return.pdf
-
Payments Canada — Explainer: Lynx wire payments and the Payment Confirmation Reference Number (PCRN generated only after settlement; payee availability and cutoffs): https://www.payments.ca/explainer-lynx-wire-payments-and-payment-confirmation-reference-number
-
Payments Canada — High-value payment system - Lynx statistics (2025 published totals and daily averages): https://www.payments.ca/high-value-payment-system-lynx-statistics
-
Payments Canada — System closure schedule (current business-day and statutory-holiday closures): https://www.payments.ca/system-closure-schedule
-
Bank of Canada — An Overview of Lynx (payment lifecycle, SWIFT partial copy, queues, liquidity, windows and finality): https://www.bankofcanada.ca/wp-content/uploads/2022/05/Overview-Lynx-Canadas-High-Value-Payment-System.pdf
-
FINTRAC — Reporting electronic funds transfers and Travel rule for electronic funds and virtual currency transfers: https://fintrac-canafe.canada.ca/guidance-directives/transaction-operation/eft-dt/eft-dt-eng and https://fintrac-canafe.canada.ca/guidance-directives/transaction-operation/travel-acheminement/1-eng
-
OSFI — Operational Risk Management and Resilience Guideline (critical operations, disruption tolerances, scenario testing and third-party/data risk): https://www.osfi-bsif.gc.ca/en/guidance/guidance-library/operational-risk-management-resilience-guideline
Uncertainties recorded honestly. Bank-specific channel cutoffs, fees, customer limits and internal approval rules are intentionally absent. System times are described from the Bank of Canada Lynx overview and must be checked against the current Lynx Rules and Payments Canada closure schedule before live use. The functional description of the settlement-finality rule family is deliberately non-textual; no legal wording is quoted or paraphrased here. Queue and priority mechanics are described at functional level — ordered waiting resolved by funding and priority management — without asserting system-internal algorithm detail. Figures for industry volumes are stated as orders of magnitude from public reporting, not as audited statistics. Where any of these points matters for a live decision, verify against the references above before acting.
This application uses JavaScript for the full interactive experience. This text summary is served for accessibility and search indexing.