ACSS Exceptions, Adjustments and Reconciliation. Handle clearing errors, adjustments, returns, breaks and the evidence needed for controlled reconciliation.
Canada Payments & Collections · Block 3: ACSS and Retail Batch Payments · Chapter 15 of 75
Handle clearing errors, adjustments, returns, breaks and the evidence needed for controlled reconciliation.
Every chapter before this one taught the happy path: a clean instruction, validated once, cleared once, settled once, posted once, reconciled once. This chapter teaches the working week as operations teams actually live it. The Automated Clearing Settlement System (ACSS) is live, it clears cheques and electronic items such as pre-authorised debits, direct deposits and Interac debit payments in deferred-net form, and its rules provide return processes for items within the applicable rule scope. That design choice — value moves first, objections are honoured afterwards inside defined processes — means every bank on ACSS must be as good at reversals, corrections, disputes and reconciliation as it is at origination. A bank that releases files well but handles returns poorly has an uncontrolled operational and customer-risk problem.
The working rule for this chapter is simple: for this chapter’s operating taxonomy, classify each exception as a reject, return/redirect, correction/claim or dispute — then act and preserve the evidence that links recovery to the original. Rejects stop an item before clearing and are cheap. A4 returns or redirects certain items after presentment when payment is refused or cannot be obtained. Operational corrections, clearing-error claims and participant compensation use the applicable rule or bank process; they are not one universal ACSS exception type. A6 governs disputes over returned items within its scope, with A9 arbitration available after the prescribed steps. Confuse these four and you will do the wrong thing energetically: re-pay a returned item and create a duplicate, refund a disputed item and surrender your evidence, or treat a timing break as a loss and alarm a customer for no reason.
A note on scope discipline. Rule families are described functionally here: A4 governs returned and redirected items within its stated scope; A6 covers disputes over returned items within its scope; A9 covers arbitration; B9 covers manual balancing and settlement; B10 covers tracing and clearing errors; and J10 covers intermember domestic interest claims/compensation. Exact reason definitions, windows, forms and timelines are version-sensitive, so quoted detail is limited to the current values verified in Section 6 and the live documents linked in Section 12. Pre-authorised debit and cheque specifics stay at family level; their dedicated blocks go deeper later. Lynx appears only as contrast — Canada's live high-value system settles each payment gross in real time with finality, so it has no return lifecycle comparable to batch — and RTR is out of scope except for its current pre-launch status noted below.
What you should be able to do after this chapter
After working through this chapter, you should be able to:
- explain why return rights and deferred-net settlement make exceptions a designed-in part of ACSS rather than a failure mode;
- classify any exception as a reject, return, adjustment or dispute and state the correct recovery path for each;
- describe who owns what among the originator, sending bank, receiving participant, Payments Canada systems, the Bank of Canada and service providers when something goes wrong;
- walk a returned item through its full lifecycle — detection, linked return entry, clearing of the return, unwinding, customer advice, repair or absorption;
- walk a correction or applicable claim through its full lifecycle — detection, quantification, evidence, claim or ledger action, resolution and reconciliation;
- explain how items in dispute move from bilateral resolution to formal process and, generically, to arbitration, and what evidence each stage needs;
- run three-way reconciliation — files released versus clearing evidence versus settlement and books — and route each class of break to its owner;
- design posting, suspense, accounting and customer-reporting behaviour that stays truthful while returns and adjustments are still in flight;
- place fraud, sanctions, AML and operational controls at the correct gates so prevention stays cheaper than recovery;
- interpret cutoffs and service levels as customer-impact promises and communicate misses, returns and breaks honestly;
- know what a bank must build, simulate and test — return storms, duplicate files, rule updates — before and after going live;
- find the authoritative answer in the live Payments Canada rulebook and Bank of Canada oversight material instead of memorising training slides.
For a roughly 60-minute core session, spend about 20 minutes on Section 1 and Section 8 up to the return lifecycle diagram, 15 minutes on Section 9 with the reconciliation diagram, 15 minutes on Section 11 working the three fictional stories, and 10 minutes on Section 12. The remaining sections are follow-up study that repays a second hour.
Chapter navigator
- Business context and customer need
- Participants, responsibilities and boundaries
- Initiation, validation and bank processing
- Clearing, exchange, settlement and finality
- Data, identifiers and messages
- Rules, cutoffs and service levels
- Fraud, compliance and controls
- Exceptions, investigations and recovery
- Posting, accounting, liquidity, reporting and reconciliation
- Implementation, testing and resilience
- Practical fictional Canadian examples
- Key takeaways and authoritative references
1. Business context and customer need
Start with the Friday every Canadian payroll officer knows. An employer with several thousand staff releases its direct-deposit file on Thursday. Most employees see the expected credit on Friday and think nothing of it. A handful do not: one account number was mistyped months ago, one employee closed an account after a move, one deposit is duplicated because somebody re-released the file "just to be safe." By Friday afternoon the employer's bank is handling three problems that look identical to an anxious caller — "the money didn't arrive" — but demand three different treatments. The mistyped and closed-account items will come back through clearing as returns and must be repaired and re-initiated. The duplicate is an adjustment problem: value went out twice and the extra must be recovered with a linked correction, not a casual refund that breaks the audit trail. A team that classifies first resolves all three by Monday with balanced books. A team that "just re-sends" or "just refunds" spends a fortnight untangling the second-order mess it created.
Customers experience obligations, dates and consequences: wages before the long weekend, supplier terms met, benefits disbursed with proof for the auditor. The bank experiences instructions, clearing windows, net positions, postings, returns and breaks. Exceptions are where those languages collide, because the customer wants certainty — "just fix it" — while the bank must respect a process in which value already moved and can only be unwound or corrected through defined entries with defined evidence. The professional skill is holding both truths at once: empathise with the urgency, then follow the path that repairs the books instead of the path that merely calms the phone call.
The economics explain why this chapter earns a full deep read. Prevention is measured in cents per item: a validation check, a duplicate hash, a confirmation screen. Recovery costs multiples: investigation time, customer contact, correcting entries through clearing, suspense funding while items age, management attention on escalations, and formal disputes consuming specialist time across two institutions. In a bank’s own incident reviews, compare the cost of upstream prevention with downstream investigation and reconciliation before deciding where to invest. When a product owner asks why the business case includes confirmation checks, duplicate locks or dual approval, this asymmetry is the answer.
Deferred-net settlement with return rights is what makes batch exceptions structurally different from high-value ones, and bankers who carry habits across rails get into trouble. In Lynx, each payment settles individually in central-bank money with real-time finality and is irrevocable: there is no "return" of a Lynx payment through clearing, only separately negotiated recovery with the beneficiary's cooperation. In ACSS batch, the framework provides defined processes for reversing (returns), correcting (adjustments) and contesting (disputes, arbitration) after clearing. This is not a design flaw. It is how a system clearing billions of items at low unit cost handles imperfect account data, closed accounts and absent collection authority. Return rights are the pressure valve that lets the batch engine run fast and cheap — and the price is that every participant must operate a competent reverse gear.
"Controlled reconciliation" in the chapter scope means something specific: an operation that can answer four questions about any item, any day — what happened to it, where it sits, who owns the next action, and what evidence proves the story. Controlled does not mean exception-free; no batch operation of size is. It means every exception is registered, classified on a shared taxonomy, aged visibly, worked by an owner with a deadline, and closed with linked evidence rather than hope. Auditors, finance and corporate clients feel the difference within minutes. Uncontrolled operations argue about facts. Controlled operations argue about actions, because the facts are already on record.
Exceptions also concentrate around predictable moments, and mature operators staff for them. Payroll cycles bring duplicate files and wrong-account returns. First collections against a newly acquired book bring mandate and account failures. Month-ends bring cutoff misses. Holiday weekends compress working days and stretch return handling. A corporate client's new HR platform or ERP brings format and reference breaks that surface as rejects and unmatched items. A bank can use its calendar to pre-position explanations, capacity and funding for predictable exception load.
2. Participants, responsibilities and boundaries
An exception only resolves when each participant does its bounded job and hands over clean evidence. Blurred responsibilities are how incidents start, so this section draws the boundaries crisply for the return, adjustment and dispute mechanics in Section 8.
The originator creates the economic need and, for outgoing items, the instruction — the employer for payroll, the biller for collections, the drawer for a cheque. Its exception duties are authority, accuracy and responsiveness: the instruction must be one it was entitled to give, the details must be right, and when the bank reports a return or asks for a repair, the originator must respond with corrected data rather than a demand to "try again." Banks under-invest in originator education and pay for it in repairs. A payroll administrator who understands value dates and release locks prevents the duplicate file that would consume a week of operations time. Treat originator capability as a control, not a courtesy.
The originator's bank (sending bank) owns validation, release and the consequences of release: format, mandate evidence where applicable, balance and limit checks, duplicate detection, fraud and sanctions screening, stream selection, cutoff compliance and the release record. When its own validation catches a defect, it rejects the item before clearing — cheap, fast, fully within its control. When the defect surfaces after clearing, it owns the customer conversation, the repair or re-initiation, and the reconciliation of whatever comes back. Critically, it owns the decision to stop: to reject a suspicious file, hold a duplicate release, refuse a repair that would create a second payment. A bank that cannot say no cleanly cannot operate batch safely.
The receiving participant (receiving bank) owns receipt, validation, posting and beneficiary communication — and, uniquely in batch, the return decision. When an item cannot be applied as instructed, it raises the return through clearing under the returned-and-redirected family of processes, with the reason carried in the clearing evidence. When an item can be applied, it posts subject to the rail's framework, understanding that defined return rights may still operate within their windows. Much customer anger comes from availability language at this boundary: "posted," "available" and "final" are different promises, and Section 9 separates them.
Payments Canada owns and operates the ACSS (and Lynx) under the Canadian Payments Act. It sets clearing rules, exchange mechanics and the operating calendar through by-laws, rules, standards and procedures. It does not judge the underlying business deal, hold customer accounts, or decide commercial disputes. When this chapter says "the live rule text," it means the current ACSS rules, standards and by-laws in the official rules and documentation library. Keep this boundary in mind whenever someone suggests "asking Payments Canada to reverse a payment." The operator provides the processes — returns, adjustments, disputes, arbitration — through which participants reverse, correct and contest. It does not reach into participant books on request.
The Bank of Canada touches this chapter in two roles. First, it provides settlement accounts and settlement services: ACSS net positions settle on the books of the Bank of Canada, so every batch cycle depends on direct clearers meeting their funding obligations there. A settlement break is a treasury incident with a Bank of Canada account at its centre, and Section 9 treats it accordingly. Second, as overseer under the Payment Clearing and Settlement Act: Lynx is designated systemically important, ACSS prominent. Oversight concerns system safety and resilience, not individual exceptions. "The Bank of Canada will sort out our return" is a category error — a return is a participant-to-participant process under Payments Canada rules.
Indirect participants, correspondents and service providers complete the map. Institutions that are not direct clearers reach ACSS through a direct participant's arrangements; that handoff is an interbank boundary with its own cutoff, evidence and return-handling obligations even when the customer sees one brand. Hubs, core vendors, transmission providers and screening utilities act as agents: outsourcing the work never outsources accountability. If a vendor's hub releases a duplicate file, it is the bank's duplicate. Contracts should mirror the exception taxonomy — who detects, who notifies, within what time, with what evidence — so a 2 a.m. duplicate triggers a rehearsed response, not a blame negotiation.
Two principles recur throughout. First, returns, adjustments and disputes are participant-to-participant processes; the customer relationship sits on top of them, not inside them. The sending bank translates network events into customer outcomes. Customers never touch clearing, and clearing never owes the customer an explanation. Second, every boundary needs a handoff record — channel to hub, hub to gateway, gateway to network, network to settlement, settlement to posting — each timestamped and reference-keyed. Investigations and reconciliation are only as good as these records. When a break cannot be diagnosed, the cause is usually a missing handoff record, not a mysterious network event.
3. Initiation, validation and bank processing
Most exceptions are conceived at initiation, born at validation and merely discovered downstream. The cheapest return is the one never raised; the cheapest adjustment is the duplicate file never released.
Initiation must capture intent in a form the bank can act on without guessing, and every field it collects is a future exception prevented or invited. File channels — portals, host-to-host, APIs — must enforce the minimum complete dataset: who pays, who is paid, how much, in what currency, on what value date, with what references, under what authority. They must bind authentication to the instruction and enforce release discipline: who prepared, who approved, whether dual approval applied, whether the file was already released. Duplicate release of a payroll or supplier file is the classic initiation failure no settlement engine can fix; it dies at source with file hashes, control totals, release locks and "already released" warnings that cannot be clicked through casually. Consumer channels need the same thinking in lighter form: confirm beneficiary details before first payment, separate requests for money from payments, and show future-dated instructions as warehoused with trigger dates rather than silently queued.
Initiation must also keep look-alike intents apart. A future-dated instruction is not yet releasable. A recurring instruction needs mandate linkage so each occurrence inherits authority without re-keying risk. A repaired item is not a new instruction and must carry linkage to the original. Test every channel against one question: can a reasonable user express the wrong intent by accident, and would the bank notice before release? If an administrator can re-upload last month's file without the portal noticing the identical hash, the adjustment workload arriving next week is already scheduled.
Validation is the layered gateset that earns the right to move money, and its outcomes must be explicit because each feeds a different path. Format and completeness catch structural defects. Authority confirms entitlement: mandates, dual approval, release authority. Funds and limits confirm the account can bear the debit plus fees. Duplicates compare hashes and references against recent history. Reachability confirms the destination is servable on the intended date. Risk and compliance — fraud scoring, sanctions screening, AML review — run before release, because holding before release is always cheaper than recovering after settlement. Section 7 details placement; the lifecycle point is that validation is a gate with named outcomes.
Those outcomes deserve precise handling. Accepted means the item may proceed, and the acceptance record anchors reconciliation. Rejected means the bank stopped the item and must tell the initiator why with repair-grade specificity: which item, which field, which rule, what correction unblocks it. Held means it awaits approval, funding or screening disposition, with a named owner and an expiry — never an indefinite shelf. Repaired means a defect was corrected under controlled rules and re-validated from scratch, never patched silently mid-flight. Weak banks validate silently and release hopefully, then meet their rejects downstream as returns. Strong banks reject early and keep every rejection in the instruction's history, so reconciliation can explain why an expected item never reached clearing.
Bank processing and routing turns validated instructions into releasable obligations. Enrichment adds what the network needs — routing, stream selection, value dates, charge handling, reference propagation — without erasing the original references. The routing decision applies the on-us test first: same legal entity, same core, same account hosting means no clearing and therefore no clearing exceptions, only internal posting controls and duplicate protection. Interbank items inherit their rail's full exception framework, which is why the routing decision must be recorded: when an exception arrives, operations should see which rail's process governs it. Processing also owns scheduling discipline: warehouse future-dated items against business days and cutoffs, split files so one bad item does not poison the batch, and record the release authorisation — who, when, under what limit and approval — that reconciliation ties back to when positions look wrong.
4. Clearing, exchange, settlement and finality
Everyday language collapses five distinct events into "cleared" or "completed." In exception handling, confusing them causes real harm: a customer told "it cleared" hears "finished and irreversible," while operations should ask which stream, accepted or rejected, netted into which cycle, funded at settlement, posted where, subject to what return rights.
Exchange is delivery of instructions between participants per the rail's rules: items and totals into ACSS streams on the operating calendar, with acceptance or rejection evidence per submission. A bank or gateway can produce item-level acceptance or rejection evidence at the participant boundary — the first fork in exception handling. Rejected items go back for repair; accepted items enter the applicable clearing process. Banks that treat exchange as a single yes-or-no lose this distinction and spend days reconciling files whose control totals stopped agreeing the moment one item was refused.
Clearing is the agreement and calculation layer: exchanged batch items aggregate into net participant positions due at a future settlement moment. A payment can be cleared but not yet settled, and that gap is where liquidity planning, cutoff promises and customer communication live. Returns operate here too — a return is itself an entry through clearing, recalculating positions — which is why returns show up in clearing evidence as expected reconciling items rather than surprises.
Settlement discharges clearing's obligations in central-bank money. ACSS settles deferred-net: the previous day’s net balances are settled during the morning of each business day through direct-clearer settlement accounts at the Bank of Canada. Settlement evidence is the proof value moved between participants. Settlement breaks — positions that cannot be funded or balanced as expected — are treasury incidents first and operations incidents second: they affect the whole cycle, escalate fast, and resolve with funding and balancing entries rather than per-item repairs. Section 9 covers the funding discipline that keeps them rare and the playbook for the rest.
Posting applies outcomes to accounts — customer, suspense, general ledger — and belongs to each bank, not the network. The critical discipline is truthful reflection of uncertainty: a credit posted while return rights may still operate is a different promise from one posted with finality, and statements, displays and advices must not blur it. Nothing matters more for customer trust than honest posting language during the window when value has moved but objections remain possible.
Finality is a legal and operational state, not a screen message. In Lynx it is real-time: each payment settles gross across Bank of Canada settlement accounts, irrevocable, confirmed per payment — which is precisely why Lynx has no return lifecycle. In ACSS batch, settlement completes the interbank obligation in central-bank money, but the rules provide defined post-presentment return, correction, dispute and recourse processes for items within their scope. Do not describe every item or every customer posting as reversible under A4. Beneficiary availability is a further separate decision owned by the receiving bank's posting policy. Promising a batch customer "irrevocable same-day finality" on a clearing record sells Lynx certainty on an ACSS chassis, and the complaint will arrive dressed as an operations failure when it was a promise failure.
Use these as diagnostic tools. "Debited here, not credited there" is a posting or clearing question until settlement evidence says otherwise. "The money came back" is a return with a reason in clearing evidence, not a malfunction. "The position does not fund" is a settlement event, not a repair queue. Locate the missing event before choosing the tool.
5. Data, identifiers and messages
Exceptions are resolved with references, not adjectives. Every return must join to its original, every adjustment must cite the entries it corrects, every dispute must identify the item contested, every break must trace across files, clearing evidence and books.
The foundation is end-to-end item identity: references letting every system agree an item is the same item. At initiation, originator file and item references plus control totals and value dates. Through processing, enrichment without erasure — routing added, originals carried forward, never replaced by internal sequence numbers nobody downstream can see. At exchange, acceptance records preserving sender references so rejected items are precisely identifiable. At clearing, returns, adjustments and dispute entries linked to the originals they reverse, correct or contest. At posting, customer narratives containing enough of the original reference for the customer and corporate reconciliation teams to match. Test any data design with one question: if this item returns in six weeks, can a junior operator join it to the original without fuzzy matching? If the answer needs memory or amount-and-date guessing, the design is already generating its future investigation queue.
Batch formats deserve a frank paragraph. ACSS-adjacent exchange still leans on legacy record layouts — automatic funds transfer conventions for direct deposits and pre-authorised debits, image and paper-item records for cheques — with short, rigid reference fields that are easy to truncate. Later blocks go deep; this chapter needs only the consequences. Never let conversion silently drop or reformat the reference reconciliation depends on: map fields explicitly, validate lengths, reject rather than truncate. Keep PAD and cheque items at family level in exception data so the correct process is selected, without building logic on field-level specifics quoted from memory. And preserve what the customer supplied: corporate straight-through reconciliation dies when a bank replaces a meaningful client reference with an internal batch number that appears on the statement instead.
A brief contrast clarifies. Lynx wires travel as ISO 20022 messages over the SWIFT network, and Lynx generates a Payment Confirmation Reference Number per wire — a clean system-issued handle for investigations. Batch has no equivalent universal handle, which is why batch exception data must be assembled from sender references plus clearing evidence. Design each rail's exception data around the best join key that rail actually provides, and never assume one rail's handle exists on another.
Return and adjustment linkage is the mechanical standard this chapter demands: the recovery record carries the original item reference, the original file or cycle identifier, the reason in the form the applicable process requires, and a distinct recovery reference. This is the chapter’s bank-control design standard, not a claim that every ACSS stream uses the same field set. A return that does not cite its original is operationally anonymous — no auto-match, no intelligible advice, a suspense booking that ages. A claim citing "see attached" instead of structured originals invites rejection and weeks of delay. A repair reusing the original reference reads as a duplicate; one with no link reads as an unexplained new payment. Banks enforcing linkage in hub and gateway software resolve exceptions in hours. Banks leaving it to operator discipline resolve them in weeks.
Finally, evidence retention and retrieval: clearing records, validation logs, release approvals, mandate evidence, customer communications and posting journals must be retrievable by item reference long after the cycle closed — across the full horizon in which returns, disputes and claims can still arrive. Policy and legal advice set schedules; operations guarantees retrievability. If you cannot produce the mandate, the release record or the original advice when a dispute ripens, you lose arguments you should have won. Archive by reference, index by reference, retrieve by reference.
6. Rules, cutoffs and service levels
Every return raised, adjustment claimed, dispute registered and arbitration invoked draws authority from the Payments Canada rulebook — the by-laws, rules, standards and procedures participants accept as a condition of clearing. This section maps that rulebook functionally and instils the most important habit in batch operations: read the live text, never memorise it.
The structure is straightforward at the level this chapter needs. Association By-law No. 3, the Payment Items and ACSS By-law, establishes what may travel through the system. Beneath it sit the lettered rules: the A-series governing items and handling, the B-series governing settlement and balancing, with standards and procedures carrying operational detail. Five neighbourhoods matter here, each described by function only. The A4 family, Returned and Redirected Items, applies when an item exchanged for clearing and settlement is refused or payment cannot be obtained and the drawee returns or redirects it through the prescribed process. A4 excludes the electronic POS/online/EDI/PIN-less POS/delayed-authorisation POS families and the Rule H1 sections for PAD items returned because of a payor dispute; AFT items follow Rule F1. The A6 family, Items in Dispute, permits a Negotiating Institution to place a returned item in dispute within its scope; it is not a general dispute rule for every ACSS stream. The A9 family, Arbitration, provides a formal, generally binding determination subject to the rule’s appeal and new-facts provisions. B9 covers manual balancing and settlement, B10 tracing and clearing errors, and J10 intermember domestic interest claims/compensation. PAD and cheque handling have their own rule families, so this chapter selects the path without importing their instrument-specific rights.
Use the live document for reason definitions, forms and field layouts. As verified on 2026-10-05, A6 requires written notice of a returned-item dispute within 60 calendar days after receipt by the original negotiating branch, written acknowledgment within 10 business days, and permits arbitration after 60 calendar days from the notice if the earlier steps do not resolve the dispute. A9 requires a response within 30 calendar days after notice and states that an order to pay is due within 5 business days after the report; its report is due no later than 60 calendar days after the required submissions and information are received. These are current rule-text values, not bank service levels, and must be re-verified after amendments. No generic claim should substitute for the applicable standard or procedure. If a colleague quotes a return window from memory, the correct response is appreciative and firm: "let us confirm against the current text before we promise the customer."
Cutoffs translate the operating calendar into customer promises, and most "missed cutoff" exceptions are communication design problems. Customers who see the cutoff — displayed at the channel, confirmed at release, restated on the confirmation — experience a miss as their own scheduling fact. Customers who never saw it experience the same event as a bank failure and call the contact centre, each call costing multiples of the display fix that would have prevented it. Holiday weekends, month-ends and payroll peaks deserve explicit advance cutoff communication. When a miss happens, the repair is scheduling honesty: next eligible cycle, value date restated, nobody pretending the network can be hurried.
Service levels extend the same honesty to the exception lifecycle: how fast rejects are advised with repair-grade detail, how fast returns are matched, unwound and advised, how long a claim may sit before it is chased and when it escalates to dispute, how often suspense and unmatched items are aged and at what age each class escalates. These are bank policy choices inside the rulebook's outer limits — written down, monitored, reported to operations, client service and, in summary, to corporate clients who plan reconciliation around them. A service level the bank cannot meet is worse than none: it converts a routine return into a broken promise. Set targets from measured performance and improve them with the investments in Sections 7 and 10.
The rulebook habit, once more: versions posted online are in force, and confirmation is an email away. Build it into procedures — playbooks cite families functionally and link the library rather than quoting numbers; training decks carry a "verified against the live text on" date; every amendment triggers review of affected mappings, monitors and test cases. Banks that do this absorb amendments as maintenance. Banks that memorise absorb them as incidents.
7. Fraud, compliance and controls
Exceptions and fraud share territory: both concern instructions that should not have produced their outcome. The difference is intent, and intent is often unknowable at detection. A duplicate payroll file is usually error — unless a compromised credential is testing what the bank releases. A PAD collection the payer denies is usually a mandate dispute — unless weak validation is being systematically exploited. Place controls at the correct gates so prevention stays cheaper than recovery and exceptions do not become the channel losses walk in through.
Pre-release screening is a high-leverage bank control because every downstream process assumes the released instruction was legitimate. The institution’s sanctions-screening decision must be resolved before release under its applicable legal, regulatory and risk controls: a batch item cleared against a sanctioned party is a regulatory event with reporting obligations, not an exception to unwind — a return reverses value but does not un-send a sanctions breach. Fraud scoring runs on the same side of the gate: originator behaviour, file-pattern anomalies, first-time destinations, round amounts at scale, velocity against history, with clear hold-and-review outcomes and named owners. AML monitoring spans release and post-release: structuring across files, layering through mule accounts, business profiles inconsistent with collection patterns. Validate twice, release once is the cost curve made audible.
Duplicate and anomaly detection earns its own paragraph as the highest-volume preventable exception. File hashes against recent history catch the re-released payroll. Control totals against history catch the doubled file. Per-item reference checks catch the item submitted twice inside one file. Behavioural baselines per originator — counts, totals, release times — catch the compromised session releasing at 3 a.m. The response ladder matters: block exact duplicates automatically, hold near-duplicates for originator confirmation, alert behavioural anomalies to fraud operations rather than to the originator who may be the problem. Report the block rate and investigate false positives; the metric shows whether the duplicate control is operating as designed.
Authority controls for collections carry special weight because pull payments move money the payer did not push. PAD collections need mandate evidence, agreed timing and amounts, and honest handling when payers dispute authority — family level here, detail in the dedicated PAD block. Cheque handling needs endorsement and identification discipline likewise detailed later. The general principle: authority evidenced before release and retrievable during dispute, with doubt resolving to hold, not hope. A collection operation that cannot produce mandates during a dispute wave reverses first and investigates later, funding reversals from margin while learning what its sales channel sold.
Segregation, approval and access form the human perimeter. Preparation and release should be separable, with dual approval above bank-defined thresholds as a common control against error and insider action. Release authority must be role-based and revoked promptly. Screening dispositions record the decision, reason and decider, because "released by the system" is nobody to interview after a loss. Privileged access to hubs, gateways and reconciliation tools must be logged: the operator who can release files, edit references and force-match breaks can manufacture or conceal an incident. Ordinary discipline, honestly applied, is what lets a bank tell auditors the operation is controlled rather than merely busy.
Retention and regulatory honesty close the section. Validation logs, screening dispositions, release approvals, mandates, clearing evidence, posting journals and customer communications must be retrievable by item reference across the full horizon in which returns, disputes and claims can arrive. When controls fail, report as obligations require: suspected fraud, sanctions matters, control breakdowns through their proper channels. An operation that hides misses to protect metrics discovers, via auditor or regulator, that hidden misses compound while disclosed ones get fixed. Candour is a control.
8. Exceptions, investigations and recovery
This is the core of the chapter. Read it with the taxonomy diagram beside you. Every batch exception resolves to one of four classifications, each with its own path, owner, evidence and customer story — and the most expensive mistake in the discipline is walking the wrong path with great efficiency.
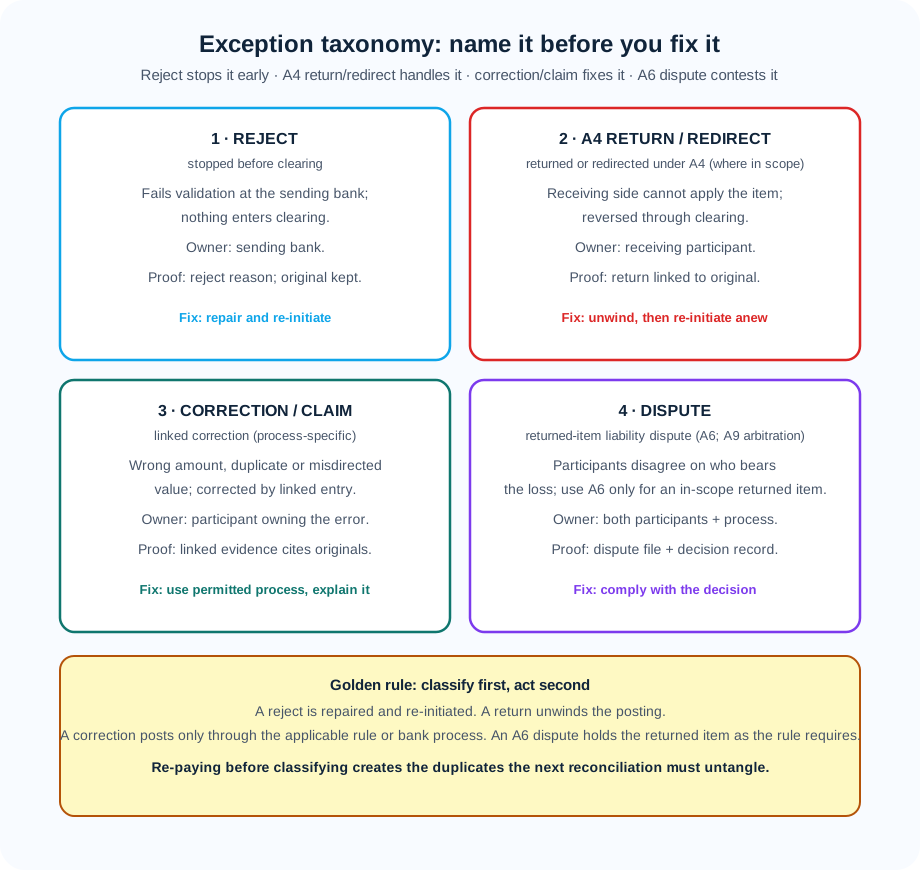
A reject stops an item before clearing: nothing left the bank; repair and re-initiate; "we held this, here is why." An A4 return routes a returned or redirected item through the rule-defined process after payment is refused or cannot be obtained: "this came back for this reason, here is the repair." A correction or claim uses the applicable ACSS rule, participant agreement or bank ledger process and must retain linkage; it is not automatically a compensation claim. An A6 dispute contests a returned item within A6 scope, with A9 arbitration after the prescribed steps; hold the returned item as the rule requires and do not promise a customer outcome before the case is decided. Hold that map. Everything below is navigation detail.
Rejects: the cheapest exception
Rejects are validation failures caught before release — the only exception class costing almost nothing, provided they are explicit. The duty is communication quality: exactly which item failed, which check, which rule, what correction unblocks it. "File rejected" is not advice. "Item 412 of 3,008: invalid account structure; correct and re-submit the item" is advice. File-level rejections need the same precision restated: which items held, which clean items released with restated control totals, what the originator does with the remainder. Record every rejection in the instruction's history so reconciliation can explain why an expected item never reached clearing — an expectation with a recorded reject is a closed loop, not a break. Measure reject rates by originator and reason: a rising rate from one client is an education or integration problem in operations costume, and a visit or specification fix beats a year of patient re-keying.
Returns: the lifecycle that defines batch operations
Returns are a major exception path in deferred-net batch. For an A4-governed item, the Drawee returns or redirects when payment is refused or cannot be obtained; the sending side then receives the return, updates its posting and advises its customer. Between lies the A4 process for an in-scope item: a return or redirect entry with the prescribed identifiers and evidence, exchanged through the applicable clearing process, with participant positions adjusted accordingly. Learn the lifecycle diagram cold.
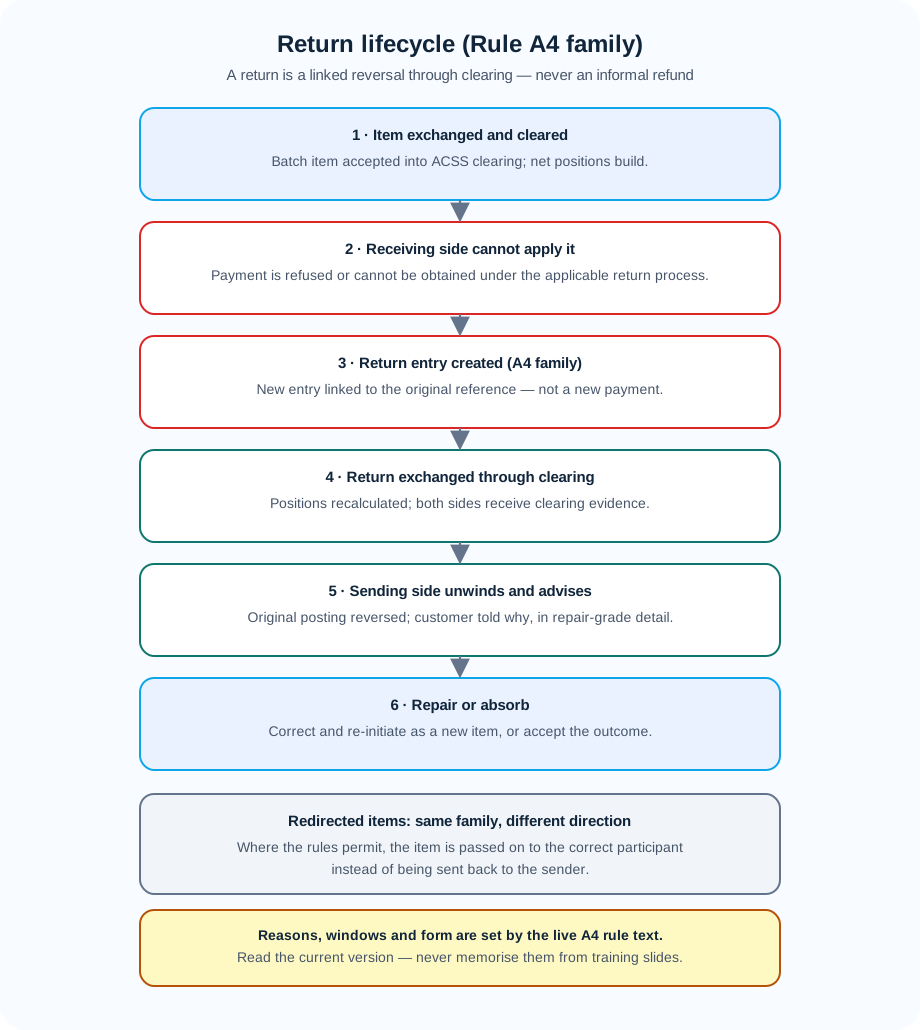
Walk the six stages as an operator. 1, exchanged and cleared: the original netted into its cycle; the sender's control totals agreed. 2, cannot apply: the Drawee applies the applicable return reason and process. Reasons live in the live A4 text and must be selected exactly — reason precision is routing, because the reason determines the possible repair. 3, return entry created: a new entry citing the original references. This linkage is the difference between a return and a mystery credit: with it, systems auto-match, unwind the right posting and generate an advice naming the original payment. Without it, the return lands in suspense and starts a needless investigation. 4, return exchanged: the return travels through clearing and positions recalculate — so the sending side learns of it after the return clears, not when the receiver decides. Customer promises must respect that lag. 5, unwind and advise: reverse the original posting, match return to original, tell the originator which item, which reason in plain language, and what correction unblocks re-initiation. 6, repair or absorb: correct the data and re-initiate as a new item with linked history, or accept the outcome and close with the unwind as final state.
Three disciplines separate competence from chaos. First, never re-pay on pressure. Parallel re-payment of an item whose return is in flight is the standard recipe for a duplicate — which then needs an adjustment, doubling the workload patience would have avoided. Second, redirect where permitted. The A4 family covers redirected as well as returned items: routing an item to the correct member or branch may avoid a repair cycle where the current A4 process permits it. Build the option into procedures. Third, advise in the customer's language with the network's facts. Corporate clients receiving repair-grade advices fix their data; clients receiving codes call back for clarification at your expense.
PAD and cheque returns stay at family level by design — payer-protection mechanics and cheque recourse belong to their dedicated blocks. This chapter requires process selection: know the item's family, raise the return under the correct process, hand off to specialists where family specifics govern. A return under the wrong family's process gets rejected, and the item ages while two sides argue procedure instead of value.
Corrections and applicable claims: preserving value and linkage
Returns and corrections are not interchangeable. An A4 return or redirect handles an in-scope item that was refused or could not be paid. A duplicate, wrong amount, misdirected value or internal posting error may require a bank ledger correction, a tracing/clearing-error process under B10, manual balancing and settlement under B9, or an intermember domestic interest/compensation claim under J10. Select the instrument from the current rule and the item family. The operational control shape remains useful: detect, contain, quantify, evidence, raise the applicable claim or correction, resolve, and reconcile.
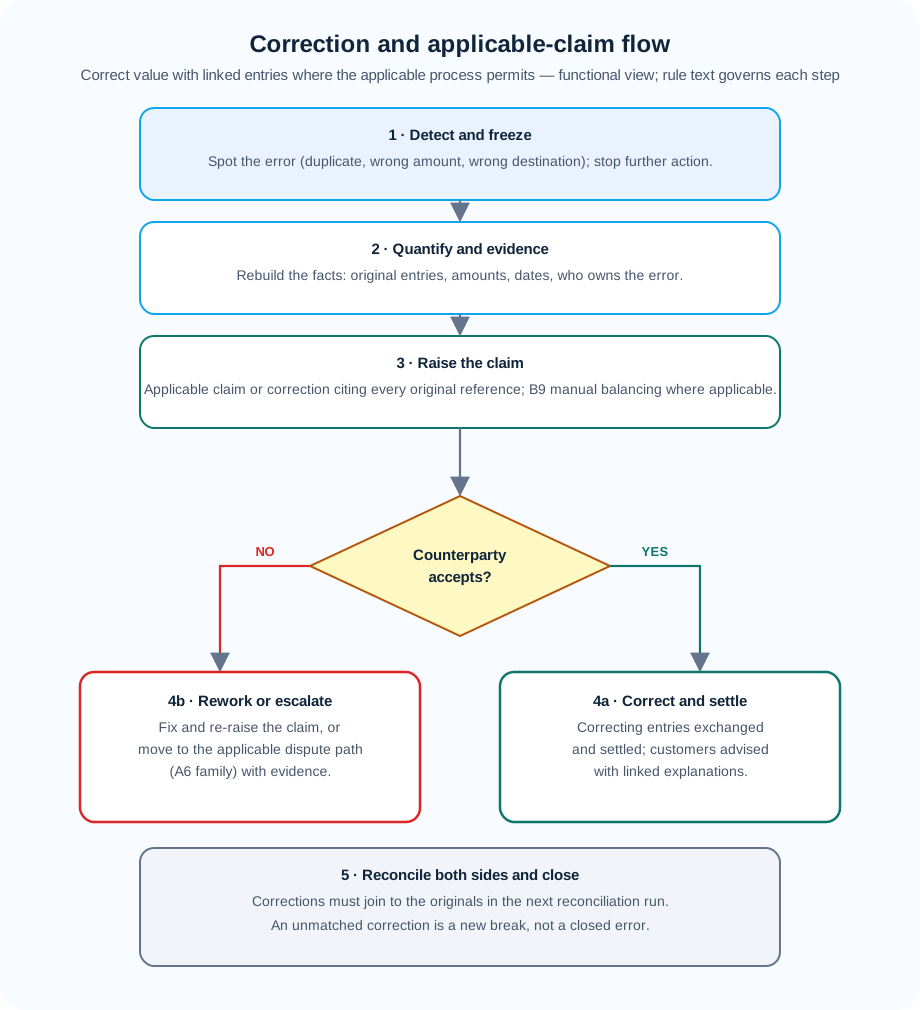
Detection and freezing is where quality is won or lost. Duplicates surface through Section 7 controls, wrong amounts through complaints or corporate callbacks, misdirected value through beneficiary confusion, imbalances through Section 9 breaks. First action is always containment: stop further action — no repair, no re-payment, no casual refund — and register the suspected error with references. Do not move more money before the suspected error is evidenced and the applicable process is selected.
Quantification and evidence rebuilds the story from records: original file and item references, clearing evidence of what moved, posting journals of where it sits, communications of what was promised. The output states the error, amount, correction direction and every original reference the counterparty needs to validate without its own investigation. A structured claim gives the counterparty enough information to validate the issue without reopening the entire investigation; an unstructured request does not.
Raising the claim follows the applicable rule or participant agreement; it does not automatically put every correction into ACSS. Preserve each original reference, the claim or case reference, amount, direction and evidence. The counterparty validates against its records. Acceptance means the agreed correction or compensation is posted and reconciled; rejection means correct and re-raise where permitted, or escalate a substantive disagreement through the applicable dispute path. Do not re-send an identical rejected claim without addressing the reason.
Reconciliation of corrections closes the loop and is the step most skipped. A correcting entry that does not join its original in the next reconciliation run remains an open break. Every adjustment procedure ends with a reconciliation check — original matched to correction, amounts netting to intent, suspense untouched — before the case closes. Adjustments are complete when reconciliation says so.
Investigations: finding facts while the customer waits
Between detection and resolution lies investigation: assembling facts across systems, participants and time for two masters — the recovery process, which needs evidence, and the customer, who needs honest updates. The method is mechanical. From the best available reference, pull every handoff record: release logs, validation outcomes, exchange acceptances, clearing evidence, settlement records, posting journals, advices. Establish the item's state in lifecycle terms — rejected, cleared, settled, posted, returned, adjusted, disputed — and the recovery path follows. Name the next-action owner in the case record. Then communicate outward: established, pending, who holds it, when the next update arrives. Customers tolerate scheduled bad news far better than silence punctuated by surprises. Never promise outcomes on assumptions about another participant's process — promise updates until evidence supports an outcome.
Cross-participant investigation adds structured counterparty contact: references, facts and a specific question — not "where is our money" but "item X, reference Y, cycle Z, no return in our evidence; please confirm application or return status." Precision gets answers; indignation gets queues. Where the rulebook provides inquiry or tracing processes for the family, use them over informal channels — formal inquiries create the evidence record a later dispute or arbitration may need. Log every contact from the first call: disputes ripening months later are won on contemporaneous notes, not recollection.
Disputes and arbitration: contesting liability by process
When participants disagree about a returned item within A6’s scope, the disagreement can move from bilateral handling to A6’s written notice, acknowledgment, escalation and dispute-resolution-panel steps. If those steps do not resolve it, the parties may proceed to A9 arbitration under the current rule. A6 excludes several electronic payment families and PAD-dispute sections, so use the item-family rule rather than treating A6 as universal.
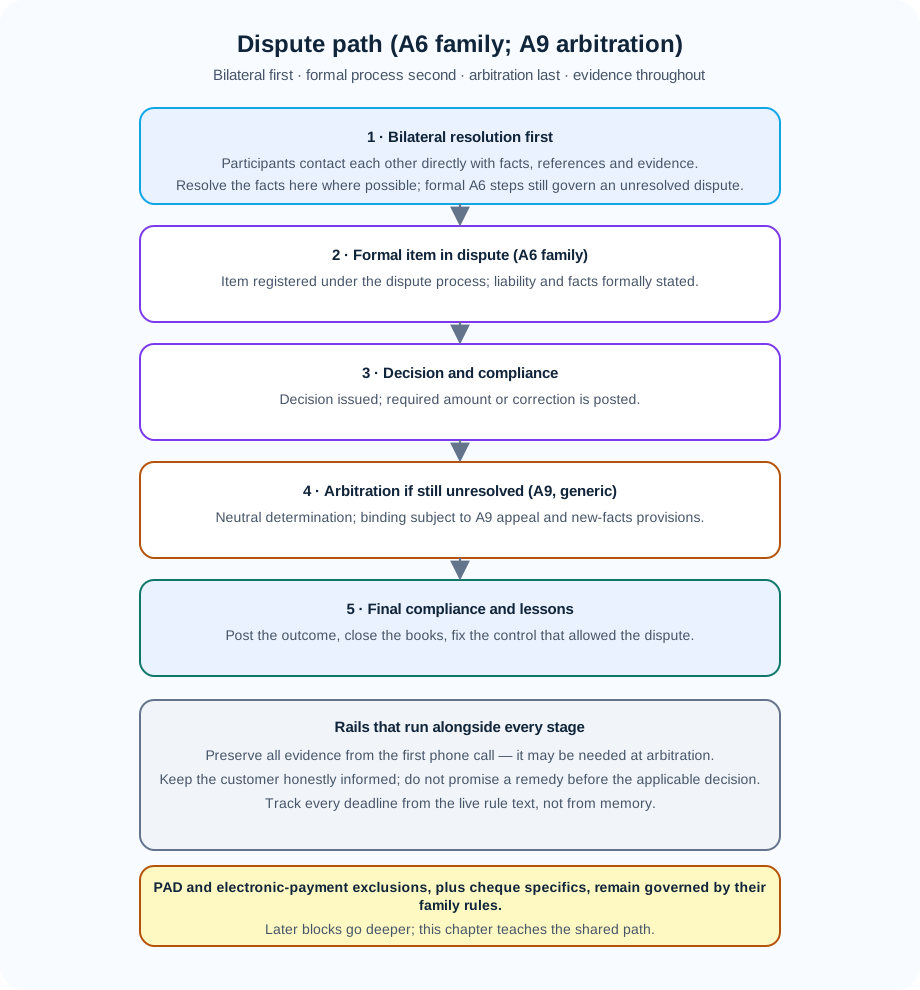
Bilateral handling is a practical first step: exchange facts and evidence, and escalate only when the parties cannot resolve the returned-item issue. Do not register a formal dispute without the evidence and authority required by the applicable process.
Formal items in dispute begin with A6’s written notice to the Drawee Branch. The returned item may not be cleared back to the Drawee Branch and must be held by the Negotiating Institution pending resolution. Track the rule deadlines, evidence and owner; any customer collection hold, reimbursement or complaint handling is a separate bank, contract, PAD or consumer-law decision and must not be inferred from A6 alone.
Decision and compliance follow the applicable panel or arbitration outcome. Under A9, the arbitration decision is final and binding subject to the rule’s court-appeal and new-facts provisions; an order to pay is due within 5 business days after the report, while the report is due no later than 60 calendar days after the required submissions and information are received. Record the decision, post the amount and any permitted interest or costs, and reconcile it. Do not describe arbitration as a universal or automatic route for every ACSS dispute.
Close every dispute with lessons learned: fix the control that allowed it. Mandate dispute waves mean mandate validation failed; handling disputes mean procedures or training failed; lost arbitrations mean evidence discipline failed. Disputes are tuition. Extract the lesson and pay once, or close the case and pay every term.
Recovery, ageing and the registers
Recovery ends in few states — name them to keep case management truthful. Repaired and re-initiated: defect corrected, new item released with linked history. Unwound and absorbed: the return or correction stands final. Adjusted and reconciled: corrections netting to intent with reconciliation confirming. Decided and complied: dispute or arbitration outcome posted. Written off: unrecoverable amount recognised under the authority matrix — governed, evidenced, never a quiet suspense burial. Open cases sit in working states with owners and next-action dates; closed cases carry ending states with linked evidence. Cases without owners age; cases without ending states accumulate.
Two registers hold the operation together. The exception register records every classified exception from detection to closure. The suspense and unmatched register records every value outside its intended account with amount, age, owner and expected path. Review both on a risk-set rhythm — daily for high-value and aged items — with escalation thresholds. Ageing analysis distinguishes timing items that may clear when linked entries arrive from value breaks that require action; an item beyond its process's outer limits is an escalation, not a monitoring entry. Report upward in summary: volumes by class, ageing buckets, write-offs, dispute inventory. Management that sees the exception operation sees the payments business as it is.
9. Posting, accounting, liquidity, reporting and reconciliation
Section 8 handled exceptions item by item. This section covers the financial and evidentiary machinery keeping the batch business truthful while exceptions fly: posting puts value on accounts, accounting keeps the bank's books honest, liquidity funds positions, reporting tells the story, reconciliation proves it.
Posting: truthful balances while rights are still open
Posting's central tension is timing: expectations pull toward immediate availability while return rights push toward caution. Receiving banks resolve it through posting policy — when credits become available, when debits become final, what language statements and displays use — and the only standard is honesty. A credit posted while defined rights may still operate must never present as irreversible. Accelerated availability as a bank-specific commercial choice — crediting before the position is beyond recall — must be governed, funded and communicated clearly; it must not arise from vague display language. Any "instant available" promise on batch-sourced funds is a bank risk and customer-communication decision.
Posting mechanics must survive exception paths without manual improvisation. Returns auto-match to originals and reverse the correct legs — principal plus whatever fee or interest policy attaches — with narratives naming the original. Adjustments post as linked corrections, never unexplained entries corporate teams cannot match. Repairs post as new items with history linkage, never reusing references in duplicate-reading ways. Suspense postings carry reason, age and owner from creation, because anonymous suspense is where breaks go to be forgotten. Test posting logic against Section 11's three stories before production does it for you.
Accounting: the bank's books under exception load
Clearing-position GL accounts must reflect returns and adjustments as linked entries so finance sees operations' story. Suspense accounts must be owned, aged and escalated — a suspense balance is a question with an owner and deadline. Fee treatment on returned and adjusted items follows stated policy: which fees stand, which reverse, who decides, how the customer is told. Write-offs travel the authority matrix with evidence attached. Period-end close includes explicit exception cutoffs: which in-flight items accrue, which provisions move, who signs that suspense and unmatched registers reconcile to the ledger. Auditors arrive asking exactly these questions. Designed answers finish audits; improvised ones repeat them.
Liquidity: funding positions that exceptions reshape
ACSS calculates net balances from exchanged items and settles the previous day’s net balances during the morning of each business day through direct-clearer settlement accounts at the Bank of Canada. Exceptions can change the expected position, making liquidity a daily discipline. Returns, adjustments and balancing entries reshape positions after forecasts: a corrected corporate duplicate, a wave of refused debits, a balancing entry moving value between participants. Three disciplines follow. Forecast with exceptions modelled — return and adjustment assumptions from history, payroll Fridays, collection peaks, month-ends — not the happy path plus improvisation. Monitor intraday against forecast with divergence alerts, detecting funding gaps forming rather than failures announced. Maintain a rehearsed settlement-break playbook: who declares, who funds, how participants are informed, how balancing completes. Treasury, settlement operations and payments operations drill it together; a playbook owned by one desk fails at the next handoff.
Reporting: telling customers and management what happened
Customer reporting — statements, advices, online detail, corporate files — must show returns and adjustments as what they are: linked to the original, reasoned, actionable. "Return, item 412, reason as advised, correct account and re-submit" lets a payroll team act that morning; an unexplained reversal burns three people's morning manufacturing the explanation the advice should have carried. Intraday and end-of-day corporate reporting should include exception content by design — rejects, returns received, adjustments posted, items awaiting repair — because client reconciliation teams plan around these inputs, and a bank reporting them reliably embeds itself in client process. Management reporting covers the Section 8 registers in summary. Regulatory and scheme reporting feeds from the same evidenced records, never from memory at deadline.
Reconciliation: proving the story end to end
The model is three-way: files released (counts, control totals, value dates, release records) against clearing evidence (participant acceptances or rejects, A4 returns, applicable claims or corrections, A6 dispute holds, and B9/B10 entries) against settlement and books (BoC-funded positions, GL entries, customer postings, suspense, fees, corrections). Match on reference, amount, date and status — all four — and treat in-flight returns and applicable claims or corrections as expected reconciling items only when each links to its original and has an owner.
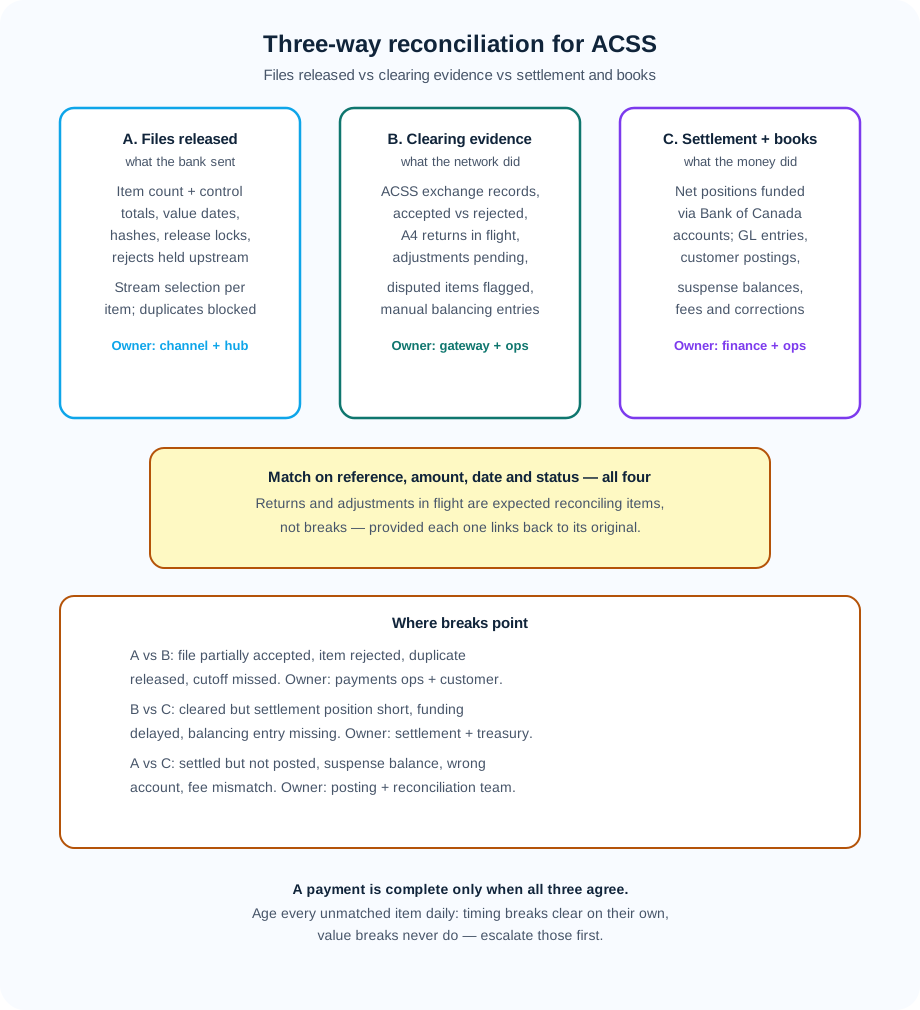
Breaks point to owners: A-versus-B (partial acceptance, rejection, duplicate release, cutoff miss) belongs to payments operations with the customer. B-versus-C (cleared but position short, funding delayed, balancing entry missing) belongs to settlement and treasury. A-versus-C (settled but unposted, suspense, wrong account, fee mismatch) belongs to posting and reconciliation teams. Route on detection, not after a general queue ages it: misrouted breaks turn one-day timing differences into three-week investigations.
Two habits keep reconciliation controlled. Age everything daily and escalate value breaks first. Some timing breaks clear as linked entries arrive; monitor them against an age and value threshold rather than assuming they will clear. Value breaks — un-netted amounts, items with no linked recovery, ownerless suspense growth — never self-heal, and each day compounds recovery cost. Close the day deliberately: define what "reconciled today" means, which in-flight items are explicitly accepted as reconciling items with owners, who signs, what carries forward with a named next action. Explicit carry-forwards are controlled; ignoring the unmatched tail is a story told to the system, corrected at month-end with interest.
10. Implementation, testing and resilience
Banks acquire competent exception operations by building systems that enforce the taxonomy, simulating feared failures, rehearsing dreaded incidents and staffing the desks — not by writing procedures. Exception controls are cheaper to test before volumes grow, so build them into the processing design.
Build the taxonomy into systems, not manuals. Hubs and gateways should classify exceptions on receipt from clearing evidence and route each class to its queue with owner, deadline monitor and evidence template attached. Returns auto-match on linkage with defined manual tolerance. Adjustments carry claim-correction linkage as structured data, not free text. Disputes open case files with deadline calendars from the live rule text. Reconciliation runs the three-way match with class-based break routing. Size queues, staffing and auto-matching for the return storm — hundreds of linked returns from one failed corporate file — not the average day. Storms convert manual workarounds into backlogs overnight.
Test exception paths like origination. Harnesses should simulate the catalogue: file- and item-level rejects, family-level returns, duplicate files, misdirected value needing claims, counterparty claim rejections, dispute registrations, position divergences, suspense ageing. Regression suites cover every amendment touching the A4, A6, A9 and B-family neighbourhoods — mappings, monitors, layouts, balancing logic — because an untested amendment can create a production exception. End-to-end tests prove customer-visible outcomes: advices naming originals, matching statement narratives, linked corporate-file references. And test the human path: staffing, contact lists, escalation matrices, write-off and dispute-strategy authorities. Systems passing technical tests but handing unworkable queues to untrained night staff fail their first real incident.
Resilience means continuing to classify, work and reconcile while degraded: redundant exception-queue capture across hub failover so no return or claim is lost; reference-keyed idempotency so replays and retries cannot duplicate; reconciliation runnable on backup feeds with explicitly degraded confidence rather than stopped; customer and counterparty communication templates so technical outages do not become customer-information gaps; and a settlement-break drill cadence owned jointly by treasury, settlement and payments operations. Staffing resilience matters equally — expertise concentrates in few senior operators, and they take holidays. Cross-train, document judgement calls, roster so storms never meet skeleton crews holding undocumented knowledge.
Change and vendor management close the section because exception operations change constantly. Client migrations — new HR platforms, ERPs, formats — arrive as exception waves unless onboarding runs validation pilots, parallel runs and reference-mapping sign-off. Vendor and hub upgrades regression-test against the exception catalogue with rollback criteria in exception terms: degraded auto-matching or unclassified return queues mean rollback. Rule amendments trigger the Section 6 review cycle — mappings, monitors, test cases, decks, customer communications — with a named owner and completion before effect. Assign a named owner for each change and evidence completion before the effective date.
11. Practical fictional Canadian examples
Theory classifies; stories teach judgement. All three examples below are fictional — invented companies and figures, realistic mechanics — each exercising a different path: a duplicate file needing adjustment, a wrong-account item needing return and repair, a settlement-level break needing treasury-grade investigation. For each, ask the chapter's questions in order: classification, next-action owner, evidence linking recovery to original, what the customer hears.
Example (fictional): the duplicate payroll file
Northwind Outfitters Ltd., a fictional Edmonton retailer with about 1,200 staff, releases its biweekly payroll file on Wednesday afternoon: 1,200 credits totalling CAD 1.9 million for Friday value. It validates cleanly and releases with confirmation. Thursday morning, the payroll administrator — covering for a colleague, working from a desktop-saved copy — uploads the same file again "to make sure it went." The portal, lacking a duplicate hash check, accepts it as new. Validation passes: well-formed, funded, authorised. Two identical files queue for Friday clearing.
Friday brings 1,200 double-paid employees, honest callbacks and a quieter set of rapid withdrawals. Detection comes from the employer's treasurer at 10 a.m., not from controls that were never built. Containment starts immediately: remaining unsettled legs of the second file are held where the cycle permits, and every item from both files is registered as a suspected duplicate pair. Quantification follows from records — identical hashes confirming diagnosis — with clearing evidence showing what moved and journals showing double credits. Recovery uses the bank’s controlled duplicate-remediation and applicable participant-claim process, linked item by item to both file references; it is not an unexplained refund. Overpaid-employee collection runs through the employer's prompt, honest, legally advised communication — not unilateral debits the bank has no authority to raise. Reconciliation tracks duplicated legs and corrections as explicit reconciling items until every pair nets to the single intended payment.
The lessons are the chapter in miniature. A hash check and release lock would have cost a fraction of the recovery: two weeks of operations time, treasury attention on the funding swing, goodwill spent calming 1,200 households. Classification mattered: nothing was misapplied to wrong accounts, so there was nothing to return — only excess value to correct by adjustment. And the customer conversation mattered as much as mechanics: the employer needed repair-grade honesty about what happened, what was being recovered, and which portal controls would prevent recurrence — built with the employer's pilot testing before the next cycle.
Example (fictional): the wrong-account supplier return
BlueHarbour Foods Inc., a fictional Halifax seafood distributor, pays a new supplier — fictional Fundy Packaging Co-op — CAD 84,000 by AFT credit on Tuesday, keyed from an emailed invoice with one transposed digit. Validation passes: valid structure, within limits, dual approval recorded. Clearing accepts. Wednesday the receiving participant cannot apply it and raises an A4-family return with the reason in clearing evidence. The return clears through its own cycle mechanics, and the sender's auto-matching joins it to the original that evening.
Thursday morning shows quality. The sending bank unwinds its posting, reverses the fee per stated policy, and sends repair-grade advice: which payment, which amount, which reason in plain language, exactly what correction unblocks re-initiation — confirm account details through a trusted channel, correct the digit, re-submit as new. The clerk asks the bank to "just fix the digit and resend." The bank declines to edit beneficiary details on a released payment — the control existing precisely for this moment, when invoice-manipulation fraud is indistinguishable from error — and holds the line: verified details, then a new instruction. The supplier confirms through a verified channel, the distributor re-initiates Thursday for the next eligible cycle, goods release against the corrected arrival. Reconciliation shows original, linked return and repair as three joined entries.
Note the restraint, because restraint is the skill. No parallel re-payment alongside the in-flight return. No edited released instruction. No same-day-finality promise on a batch repair. The delay cost two days of supplier goodwill against the counterfactual the fraud section warns about: a same-day "fix" to unverified details sending CAD 84,000 wherever a manipulator nominated. The example illustrates why controlled verification is preferable to an unverified same-day repair.
Example (fictional): the settlement break investigation
Fictional mid-size direct clearer Meridian Trust closes a heavy month-end Monday — thousands of PAD debits plus payroll credits. Tuesday's settlement preparation shows funding materially above treasury's forecast, and the forecast-error hypothesis does not survive the data. Three-way evidence: files match clearing on counts and totals, so origination is clean; clearing versus settlement expectation diverges on one corporate collection file whose returns arrived late and whose balancing entries have not landed. Classification: a B-versus-C break — clearing evidence and settlement or ledger expectations are unbalanced — owned jointly by settlement operations and treasury, with payments operations supporting.
Response follows the playbook, not improvisation. Treasury confirms and maintains the required settlement balance while diagnostics proceed, documenting the rationale; settlement obligations are not waived by an investigation. Settlement operations confirms the missing balancing entries with counterparties through structured, referenced contact. Payments operations ages in-flight returns and adjustments as explicit reconciling items so the next run tells a true story. By Wednesday the entries land, the position trues up, and the close records the cause: a collection file whose return profile exceeded model assumptions. The lasting fix is a model change — return-rate assumptions by client and cycle type with month-end uplifts — plus a divergence alert paging before the funding desk finds the gap. No customer heard anything untrue, because no customer needed telling: the break lived and died in the settlement layer, exactly where design says such breaks belong. That containment is the point.
12. Key takeaways and authoritative references
Twelve points carry the chapter. Pin them where your team can see them.
- Exceptions are designed in, not bolted on. Deferred-net settlement with return rights makes reversals, corrections and contests part of the product. Staff, system and budget for them like any other volume.
- Classify first, act second. Reject, A4 return/redirect, applicable correction or claim, and in-scope A6 dispute have different owners and evidence requirements.
- Rejects are cheap; make them explicit. Repair-grade reasons, recorded history, restated control totals, originator education. Every explicit reject is a return that never happened.
- Returns use the applicable rule process, never an informal refund. For an A4-governed item, preserve the linkage and do not re-pay in parallel with a return in flight.
- Corrections use the applicable instrument, never a casual refund. Freeze, quantify, evidence, use the permitted claim or ledger process, correct, and reconcile. An unmatched correction remains a break.
- In-scope A6 disputes run on evidence. Handle the returned item under A6, then use A9 only after the prescribed steps if unresolved. Preserve evidence and comply with the current rule.
- Post honestly while rights are open. Posted, available and final differ. Suspense carries reason, age and owner from birth.
- Fund the positions exceptions reshape. Forecast with return assumptions, monitor intraday, rehearse the settlement-break playbook across treasury and operations.
- Reconcile three ways, route breaks to owners, escalate value first. Files versus clearing evidence versus settlement and books; monitor timing breaks to an age threshold and escalate value breaks immediately.
- Prevent upstream, where it is cheap. Hashes, locks, dual approval, beneficiary confirmation, mandate evidence, pre-release screening. Measure block and reject rates by originator.
- Read the live rule text; never memorise it. Reasons, windows, forms and timelines change. Playbooks cite families functionally, link the library, carry verification dates.
- Close deliberately. Every case ends in a named state with linked evidence; every day ends with explicit carry-forwards; every dispute ends with a control fix.
Authoritative references
Official sources only — these links outrank anything quoted from memory, including from this chapter. All listed links were checked against the live sites on 2026-10-05; if a URL moves, start from the Payments Canada or Bank of Canada home page and navigate to the named document.
- Payments Canada — Payment systems overview (ACSS retail batch and Lynx high-value systems): https://www.payments.ca/systems-services/payment-systems
- Payments Canada — Retail batch payment system (direct/indirect clearers, prior-day net settlement during the morning, ACSS items and current 2025 statistics): https://www.payments.ca/systems-services/payment-systems/retail-batch-payment-system
- Bank of Canada — Settlement account policies for Payments Canada payment systems (ACSS settlement accounts and settlement in central-bank money): https://www.bankofcanada.ca/core-functions/financial-system/bank-canadas-settlement-account-policies-for-payments-canada-payment-systems/
- Payments Canada — Real-Time Rail payment system (Q4 2026 launch target, current solution-assurance testing and onboarding status): https://www.payments.ca/systems-services/payment-systems/real-time-rail-payment-system
- Payments Canada — High-value payment system Lynx (RTGS model, irrevocability and real-time finality, ISO 20022 messaging, participant and oversight roles — the contrast case for batch return rights): https://www.payments.ca/systems-services/payment-systems/high-value-payment-system-lynx
- Payments Canada — Rules and documentation library (ACSS rules, standards, procedures and by-laws; the page states that versions posted online are in force and identifies the ACSS rules as updated effective July 27, 2026): https://www.payments.ca/systems-services/rules-documentation
- Payments Canada — Rule A4, Returned and Redirected Items (current PDF, updated/effective July 27, 2026): https://www.payments.ca/sites/default/files/a4eng.pdf?v=1785157876
- Payments Canada — Rule A6, Items in Dispute (current PDF, updated November 25, 2024): https://www.payments.ca/sites/default/files/a6eng.pdf?v=1732546374
- Payments Canada — Rule A9, Arbitration (current PDF, updated November 25, 2024): https://www.payments.ca/sites/default/files/a9eng.pdf?v=1732546415
- Payments Canada — Rule B9, Manual Balancing and Settlement; Rule B10, Tracing, Clearing Errors and Use of Photocopies; Rule J10, Intermember Domestic Interest Claims/Compensation: https://www.payments.ca/systems-services/rules-documentation
- Bank of Canada — Payment systems oversight (ACSS and Lynx roles/designations, exchange-clearing-settlement definitions and direct/indirect participation): https://www.bankofcanada.ca/regulatory-oversight/financial-market-infrastructures/payment-systems-the-bank-of-canada-oversees/
- FINTRAC — Reporting electronic funds transfers to FINTRAC (international EFT reporting obligations and transaction-reference evidence): https://fintrac-canafe.canada.ca/guidance-directives/transaction-operation/eft-dt/eft-dt-eng
- OSFI — Guideline E-21, Operational Risk Management and Resilience (critical operations, third parties and severe-but-plausible scenario testing): https://www.osfi-bsif.gc.ca/en/guidance/guidance-library/operational-risk-management-resilience-guideline
- Department of Finance Canada — Retail Payment Activities Act (Bank of Canada registration and federal PSP supervision context): https://www.canada.ca/en/department-finance/corporate/transparency/access-information-privacy/reports/rpaa-laapd.html
Diagrams in this chapter: exception taxonomy; return lifecycle (Rule A4 family); adjustment and compensation-claim flow; three-way reconciliation for ACSS; dispute path (A6 family, A9 arbitration) — all under /diagrams/payment-stories/canada/chapter-15/. Rule families are described functionally; exact reasons, windows, forms and timelines are governed by the live rule text linked above. Lynx and ACSS are live. At the 2026-10-05 audit date, Payments Canada describes RTR as launching in Q4 2026, with industry solution-assurance testing underway and participant onboarding continuing; RTR is not production capability for this chapter. PAD and cheque specifics stay at family level; dedicated blocks go deeper. Stories and companies are fictional.
This application uses JavaScript for the full interactive experience. This text summary is served for accessibility and search indexing.