Super Apps
Multi service ecosystems combining finance and daily life
One interface, several services
A super app brings multiple services into a common interface, often with payments, identity and messaging connecting them. There is no universal legal definition based on how many daily tasks it supports. The relevant obligations arise from each actual activity and entity, not the marketing label.
Financial services can sit beside transport, commerce or other tasks, making access convenient. This adjacency can also blur provider identity and encourage use without sufficient understanding. The app should explain which financial product the customer is using and where responsibility sits.
The wallet label can hide different claims
A displayed balance may be a bank deposit, stored value, e-money, promotional credit or another entitlement. It may also summarise several products. Distinguish these claims, their restrictions and protection; a combined number should not imply they are all equally withdrawable or risk-free.
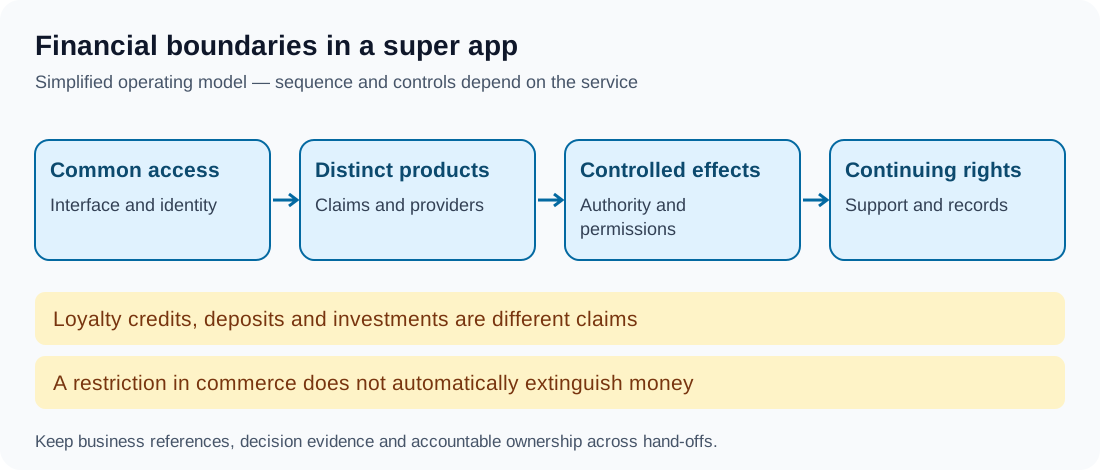
Trace funding, spending, transfers and refunds to the correct product record. Loyalty points are not automatically money held at a bank. An investment value should not silently fund spending unless a separate permitted process converts it or otherwise supplies funds.
Shared identity is not shared authority
A common login can simplify access, but compromise can affect multiple services. Apply appropriate session, enrollment, recovery and action-authority controls. Each partner should receive only the attributes and rights needed for its purpose.
Social or commerce information should not automatically become credit-assessment or marketing data. Review the actual basis, notices, permissions and sensitive inferences. User acceptance of broad app terms is not proof of unlimited lawful sharing among all services.
Separation and customer continuity
Define how a restriction in one service affects others. Fraud containment may need coordinated measures, but a commerce moderation decision does not automatically justify extinguishing a financial claim. Maintain appropriate access to money, records, complaints and support under the applicable arrangements.
Provider or platform exit should preserve residual financial obligations. Plan alternate access, record transfer, servicing and customer information. Having many suppliers does not prove resilience if they share one identity service, cloud region or middleware dependency.
Worked example: three displayed balances
In this fictional app, a customer has a payment balance, loyalty credits and a fund investment. The home screen separates the products and explains each available action. A combined overview is labelled so it cannot be mistaken for immediately spendable cash.
After the customer's shopping profile is suspended, the financial provider applies the relevant checks and supplies an appropriate independent servicing route. Support preserves the actual reasons and records instead of claiming that every balance disappeared with the shopping login.
Incentives and monitoring
Examine cross-selling at moments of urgency, checkout or financial difficulty. Easy access can improve service, but conversion is not proof of suitable or informed use. Distinguish a service alert from a commercial offer and preserve relevant choices.
Measure complete tasks, cross-service errors, permission failures, complaint transfers and customer understanding. Reconcile financial effects independently of the app's engagement dashboards. Country expansions need product-specific legal and operating review; a common interface does not establish identical rules across markets.
Public reference and application
The FDIC guidance on banking through third-party apps explains why a nonbank app and its partner bank must be distinguished when evaluating deposit insurance. The same interface can present services with different legal protections.
Takeaway
A super app can share experience while keeping financial claims and authority clear. Its convenience depends on reliable boundaries, understandable products and access that survives problems elsewhere in the ecosystem.
Continue to Merchant Ecosystems.